According to Charm.io, TikTok Shop generated $222.9m in beauty sales (skincare, makeup, fragrance and haircare) in September 2026. This is 2.2% lower than August. Haircare remained stable while makeup (-3.7%), skincare (-2.7%), and fragrance (-1.2%) all decreased.
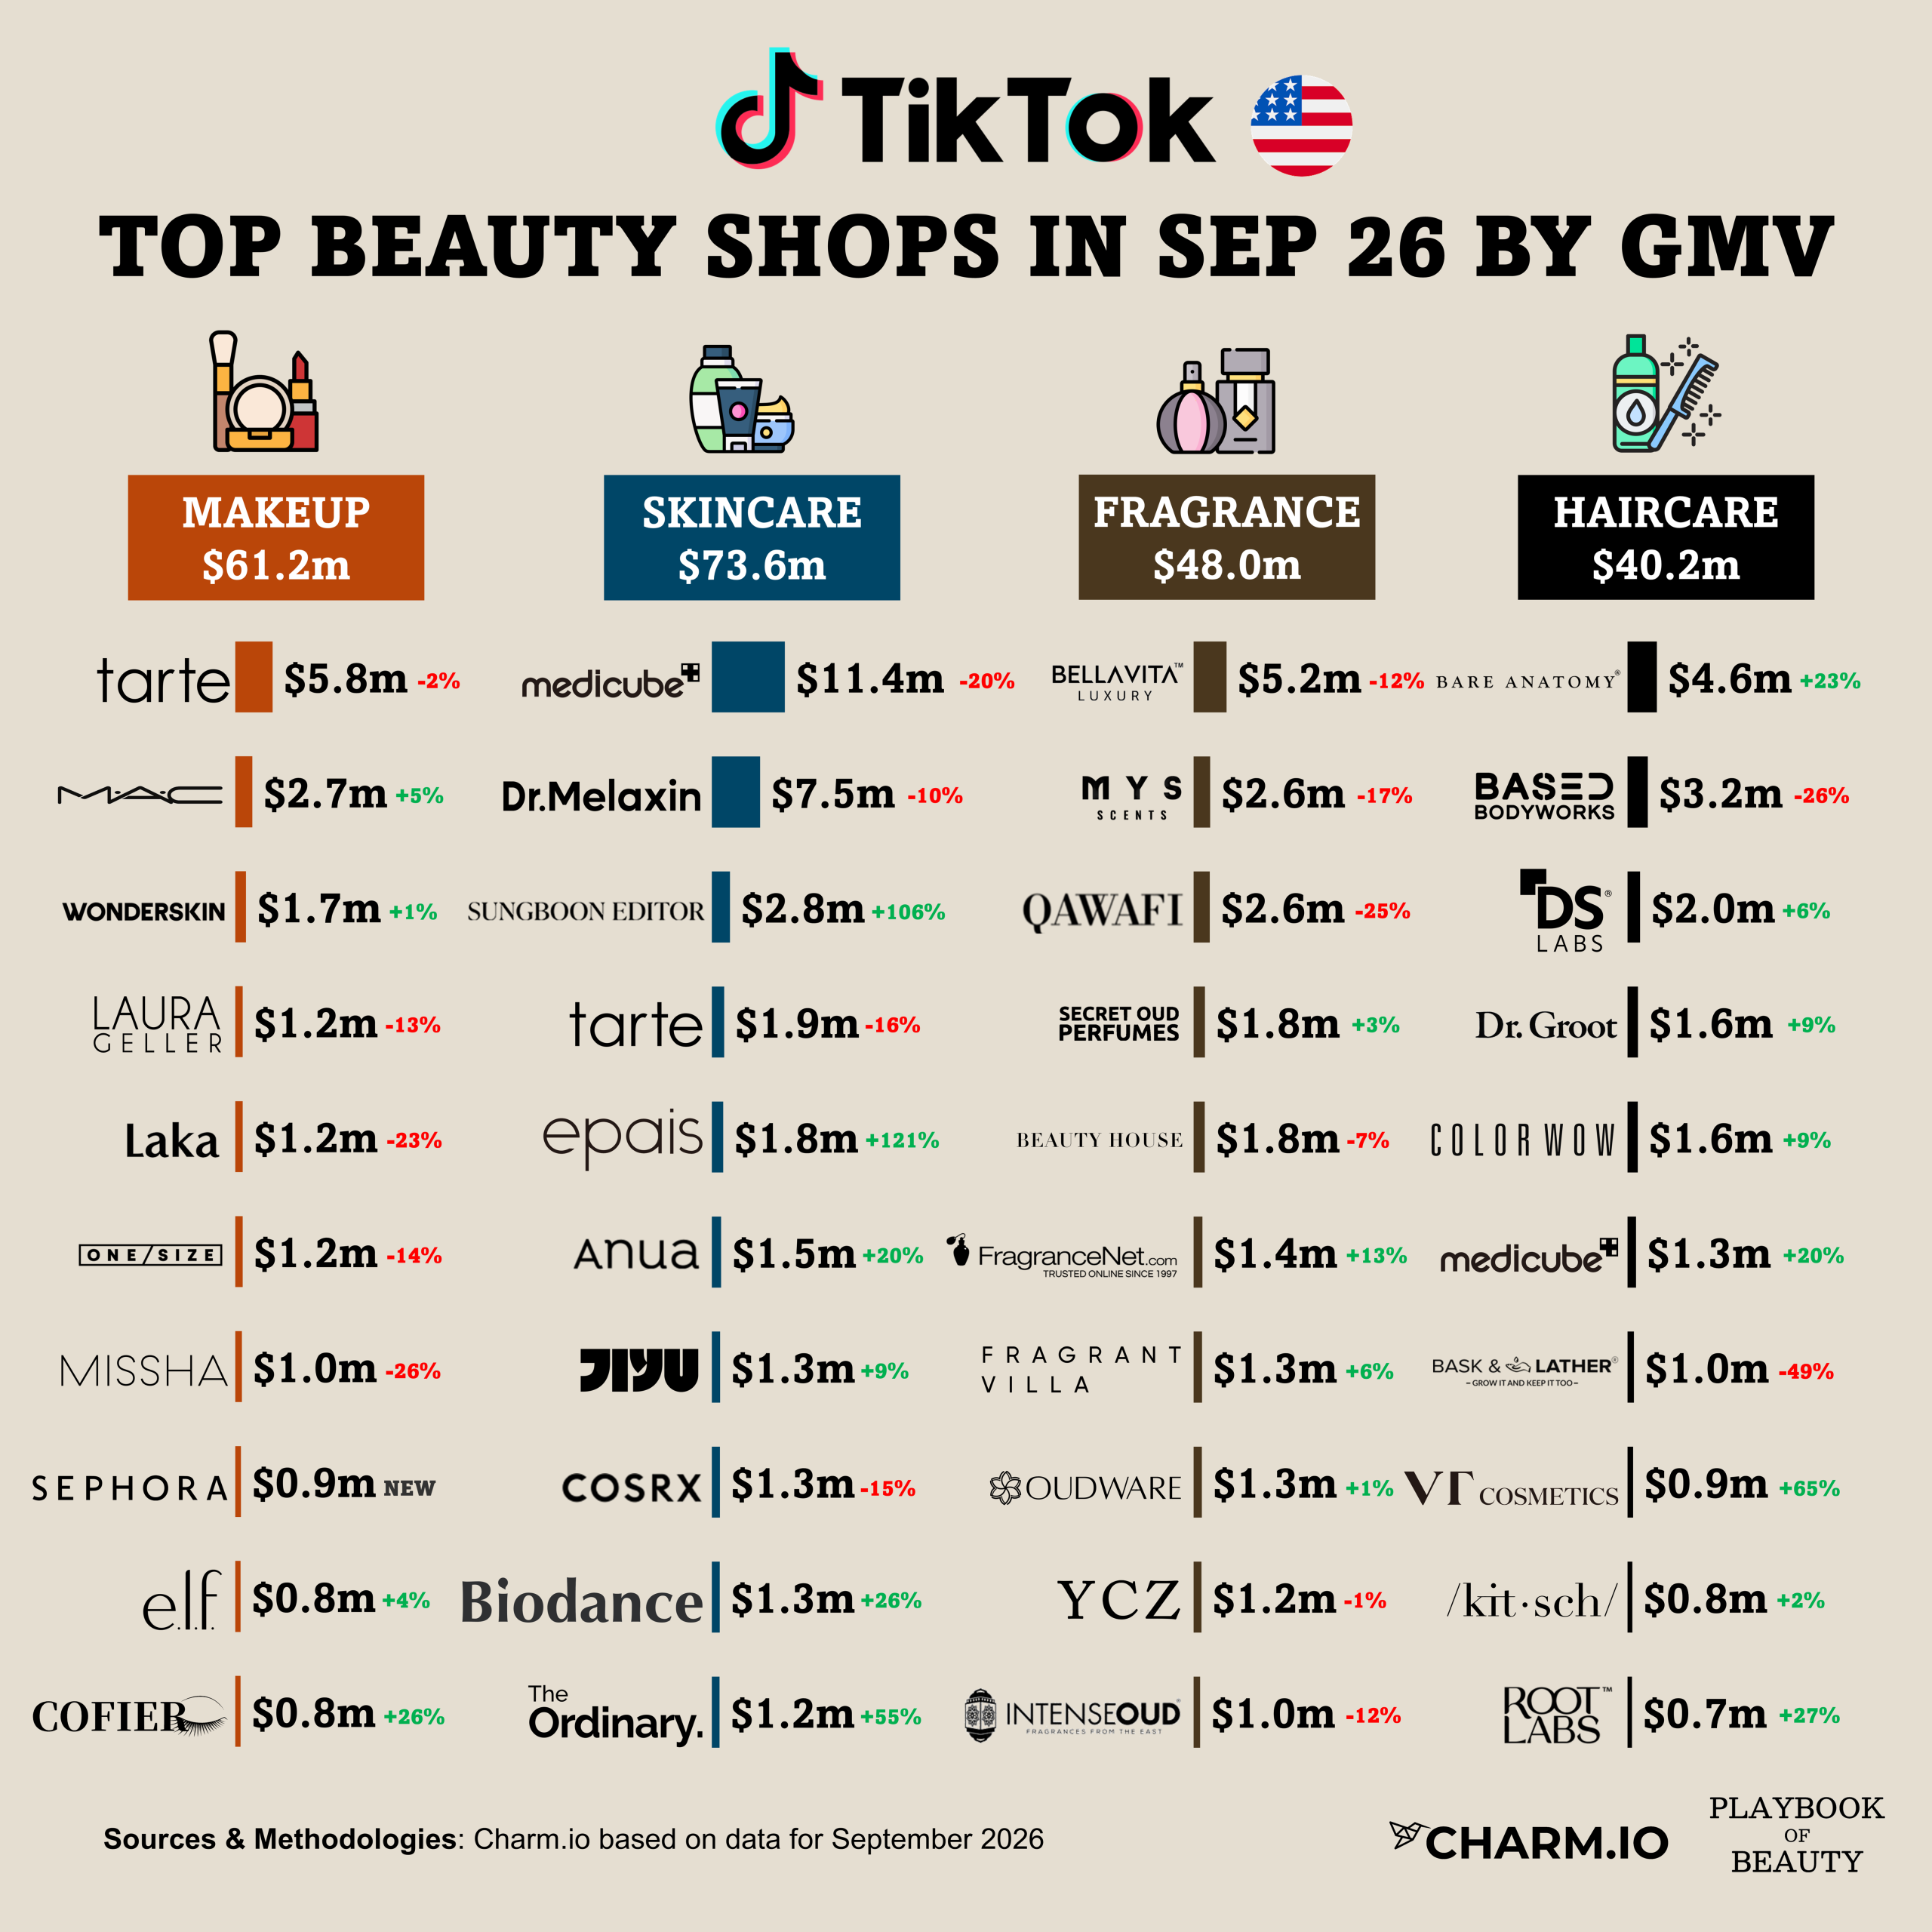
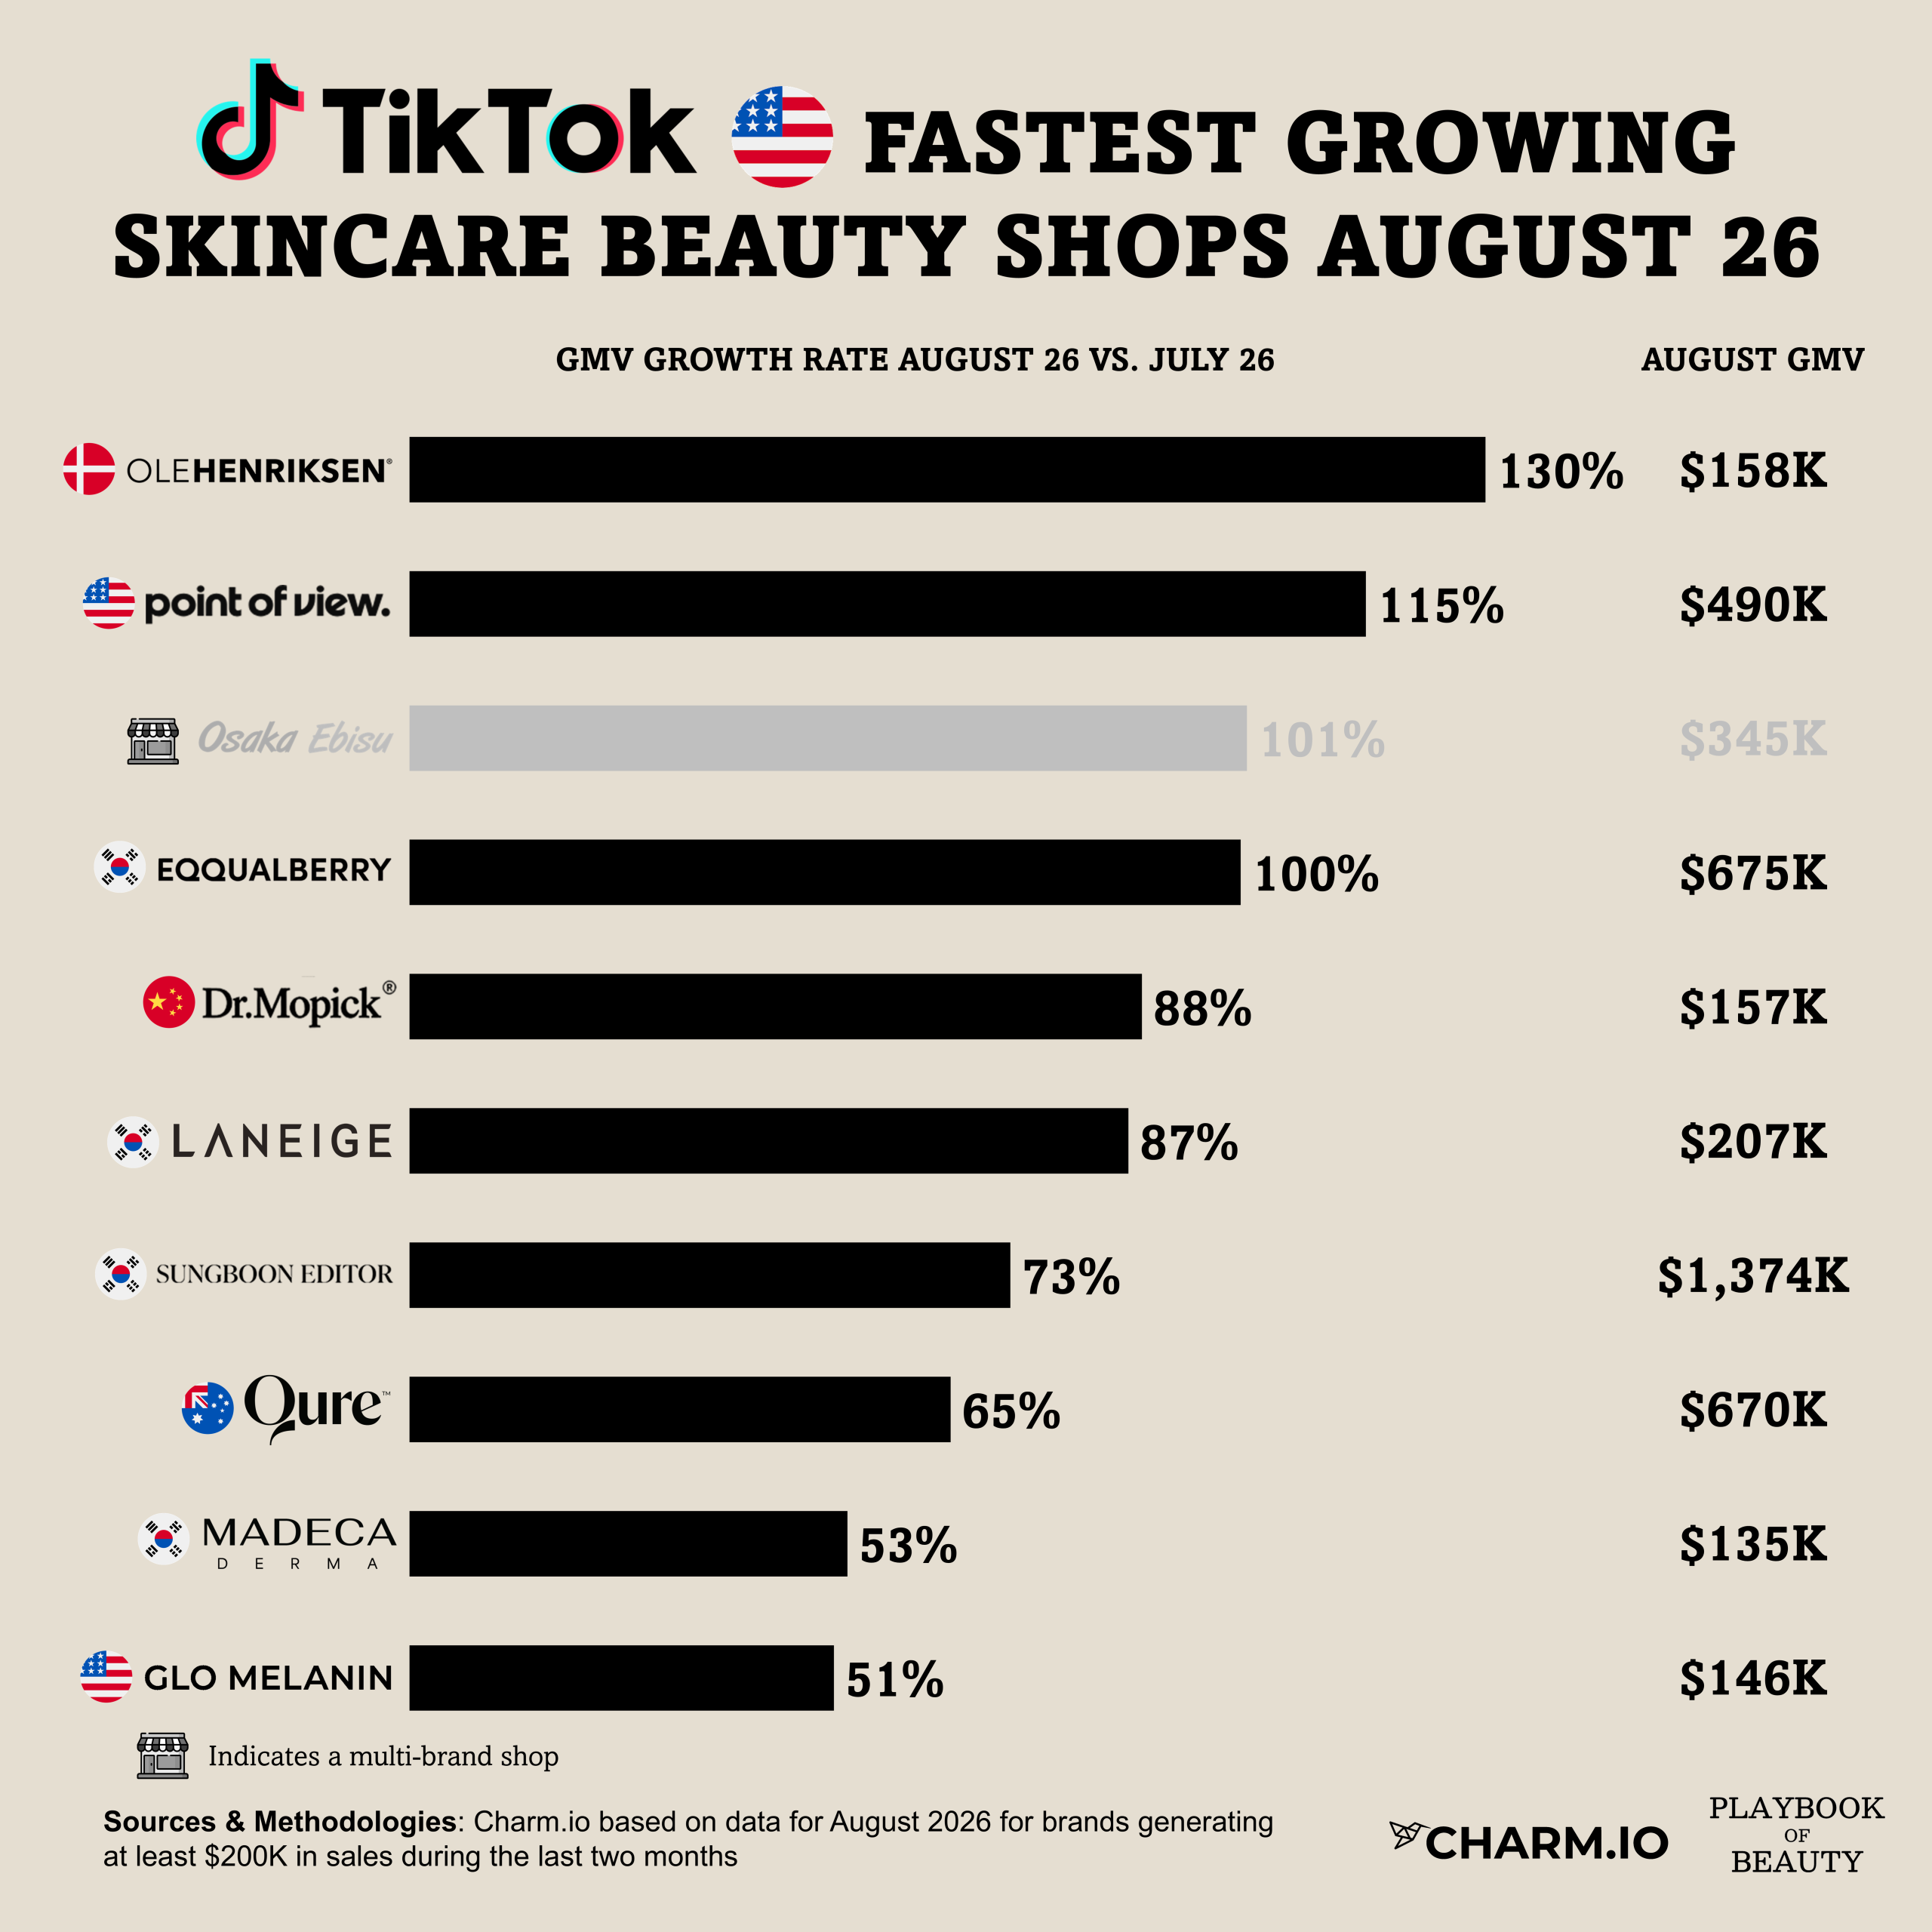
Skincare was the largest beauty category at $73.6m, down 2.7% from August. The ten top shops of the category accounted for $32.0m or 43.4% of category sales compared with 44.5% in August. Medicube and Dr.Melaxin remained the top two selling brands but sales dropped for both: Medicube by 20% to $11.4m and Dr.Melaxin by 10% to $7.5m. By contrast, Sungboon Editor sales doubled (+106% to $2.8m) and went up from 5th position to 3rd position. Three new shops made it to the top ten: epais (5th with $1.8m or +121%), Biodance (9th with $1.25m or +26%) and The Ordinary (10th with $1.22m or +55%) replacing KINTIFIC, Dr.Althea, and SKIN1004. In total, the two market leaders’ sales accounted for 25.7% of skincare sales while the second tier of shops diversified. Tarte maintained top ten position in both categories of skincare and makeup. However, Tarte skincare sales were down 16% to $1.9m.
Makeup continues to be least concentrated category as the ten top shops sold 28.2% of $61.2m of category sales, down from 29.3% in August. Tarte was still in the top position with $5.8m (-2%), followed by MAC with $2.7m (+5%). Sephora which launched on TikTok Shop on September 19th generated $887k in twelve days ranking 8th. However, 87% of sales came from its Advent Calendar, and 5 SKUs out of 42 generated 99.5% of sales so we will have to see how Sephora continues performing on the platform beyond this viral moment. Cofier Lashes entered at #10 position with $822k (+26%). Sephora and Cofier Lashes replaced Clinique and KEYYOU SHOP. The ranking still leans toward established brands, but these entrants broaden it to include a retailer and a specialist lash shop.
Sales of fragrance were down 1.2% to $48.0m with the ten leading shops accounting for $20.3m or 42.3% of category sales, down from 46.4% in August, the largest drop in top-ten concentration in the month. All ten shops in August were also in the top 10 September ranking, however MYS Scents moved from third to second position. Sales of the top three shops were down: BellaVitashop dropped 12% to $5.2m, MYS Scents dropped 17% to $2.6m and QAWAFI 25% to $2.6m. FragranceNet (+13%) and Fragrant Villa (+6%) increased sales but it wasn’t enough to make up for the drops of leading shops.
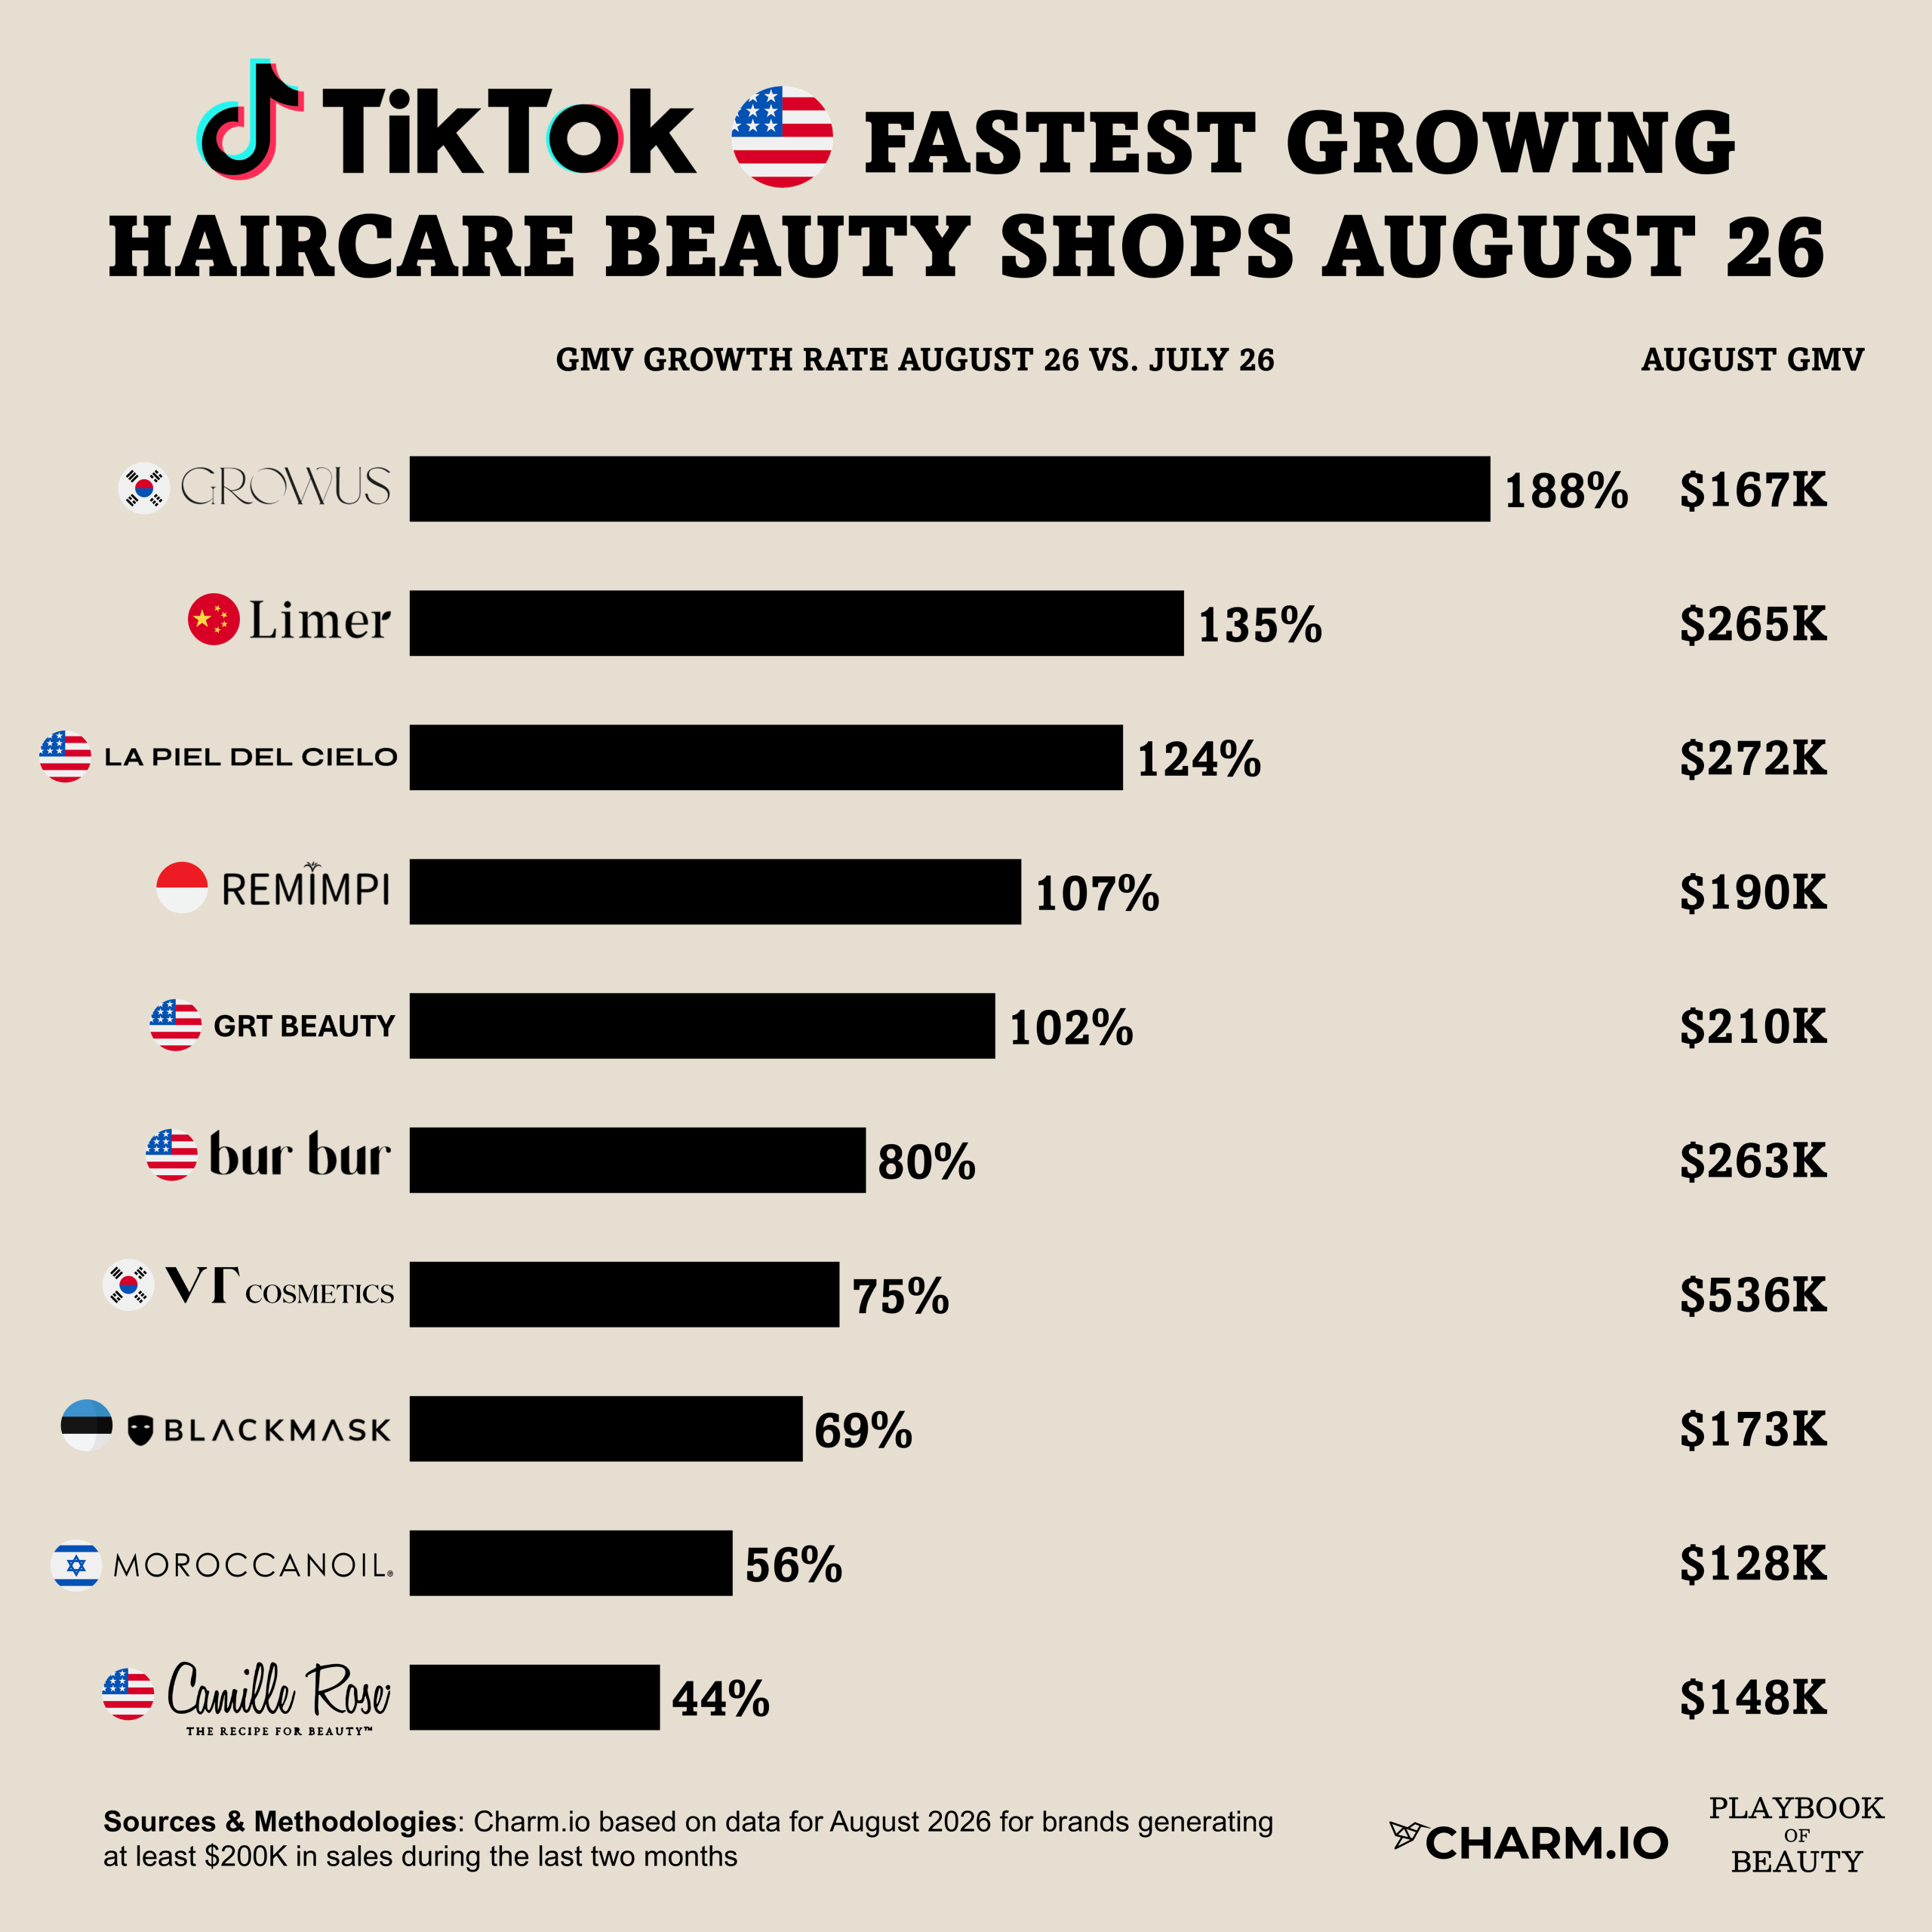
Haircare sales were flat at $40.2m. Haircare became the beauty category with the highest share of sales made by the top-ten shops in September, narrowly beating skincare (43.4%). Bare Anatomy overtook BASED for first place, increasing sales by 23% to $4.6m while BASED fell 26% to $3.2m. The ten leading shops generated $17.6m or 43.8% of category sales, down from 44.4% in August. VT Cosmetics US joined the top ten at #8 position with $884k or +65% increase replacing Simplymandys. Medicube’s haircare shop sales increased by 20% to $1.3m growing from seventh to sixth position.