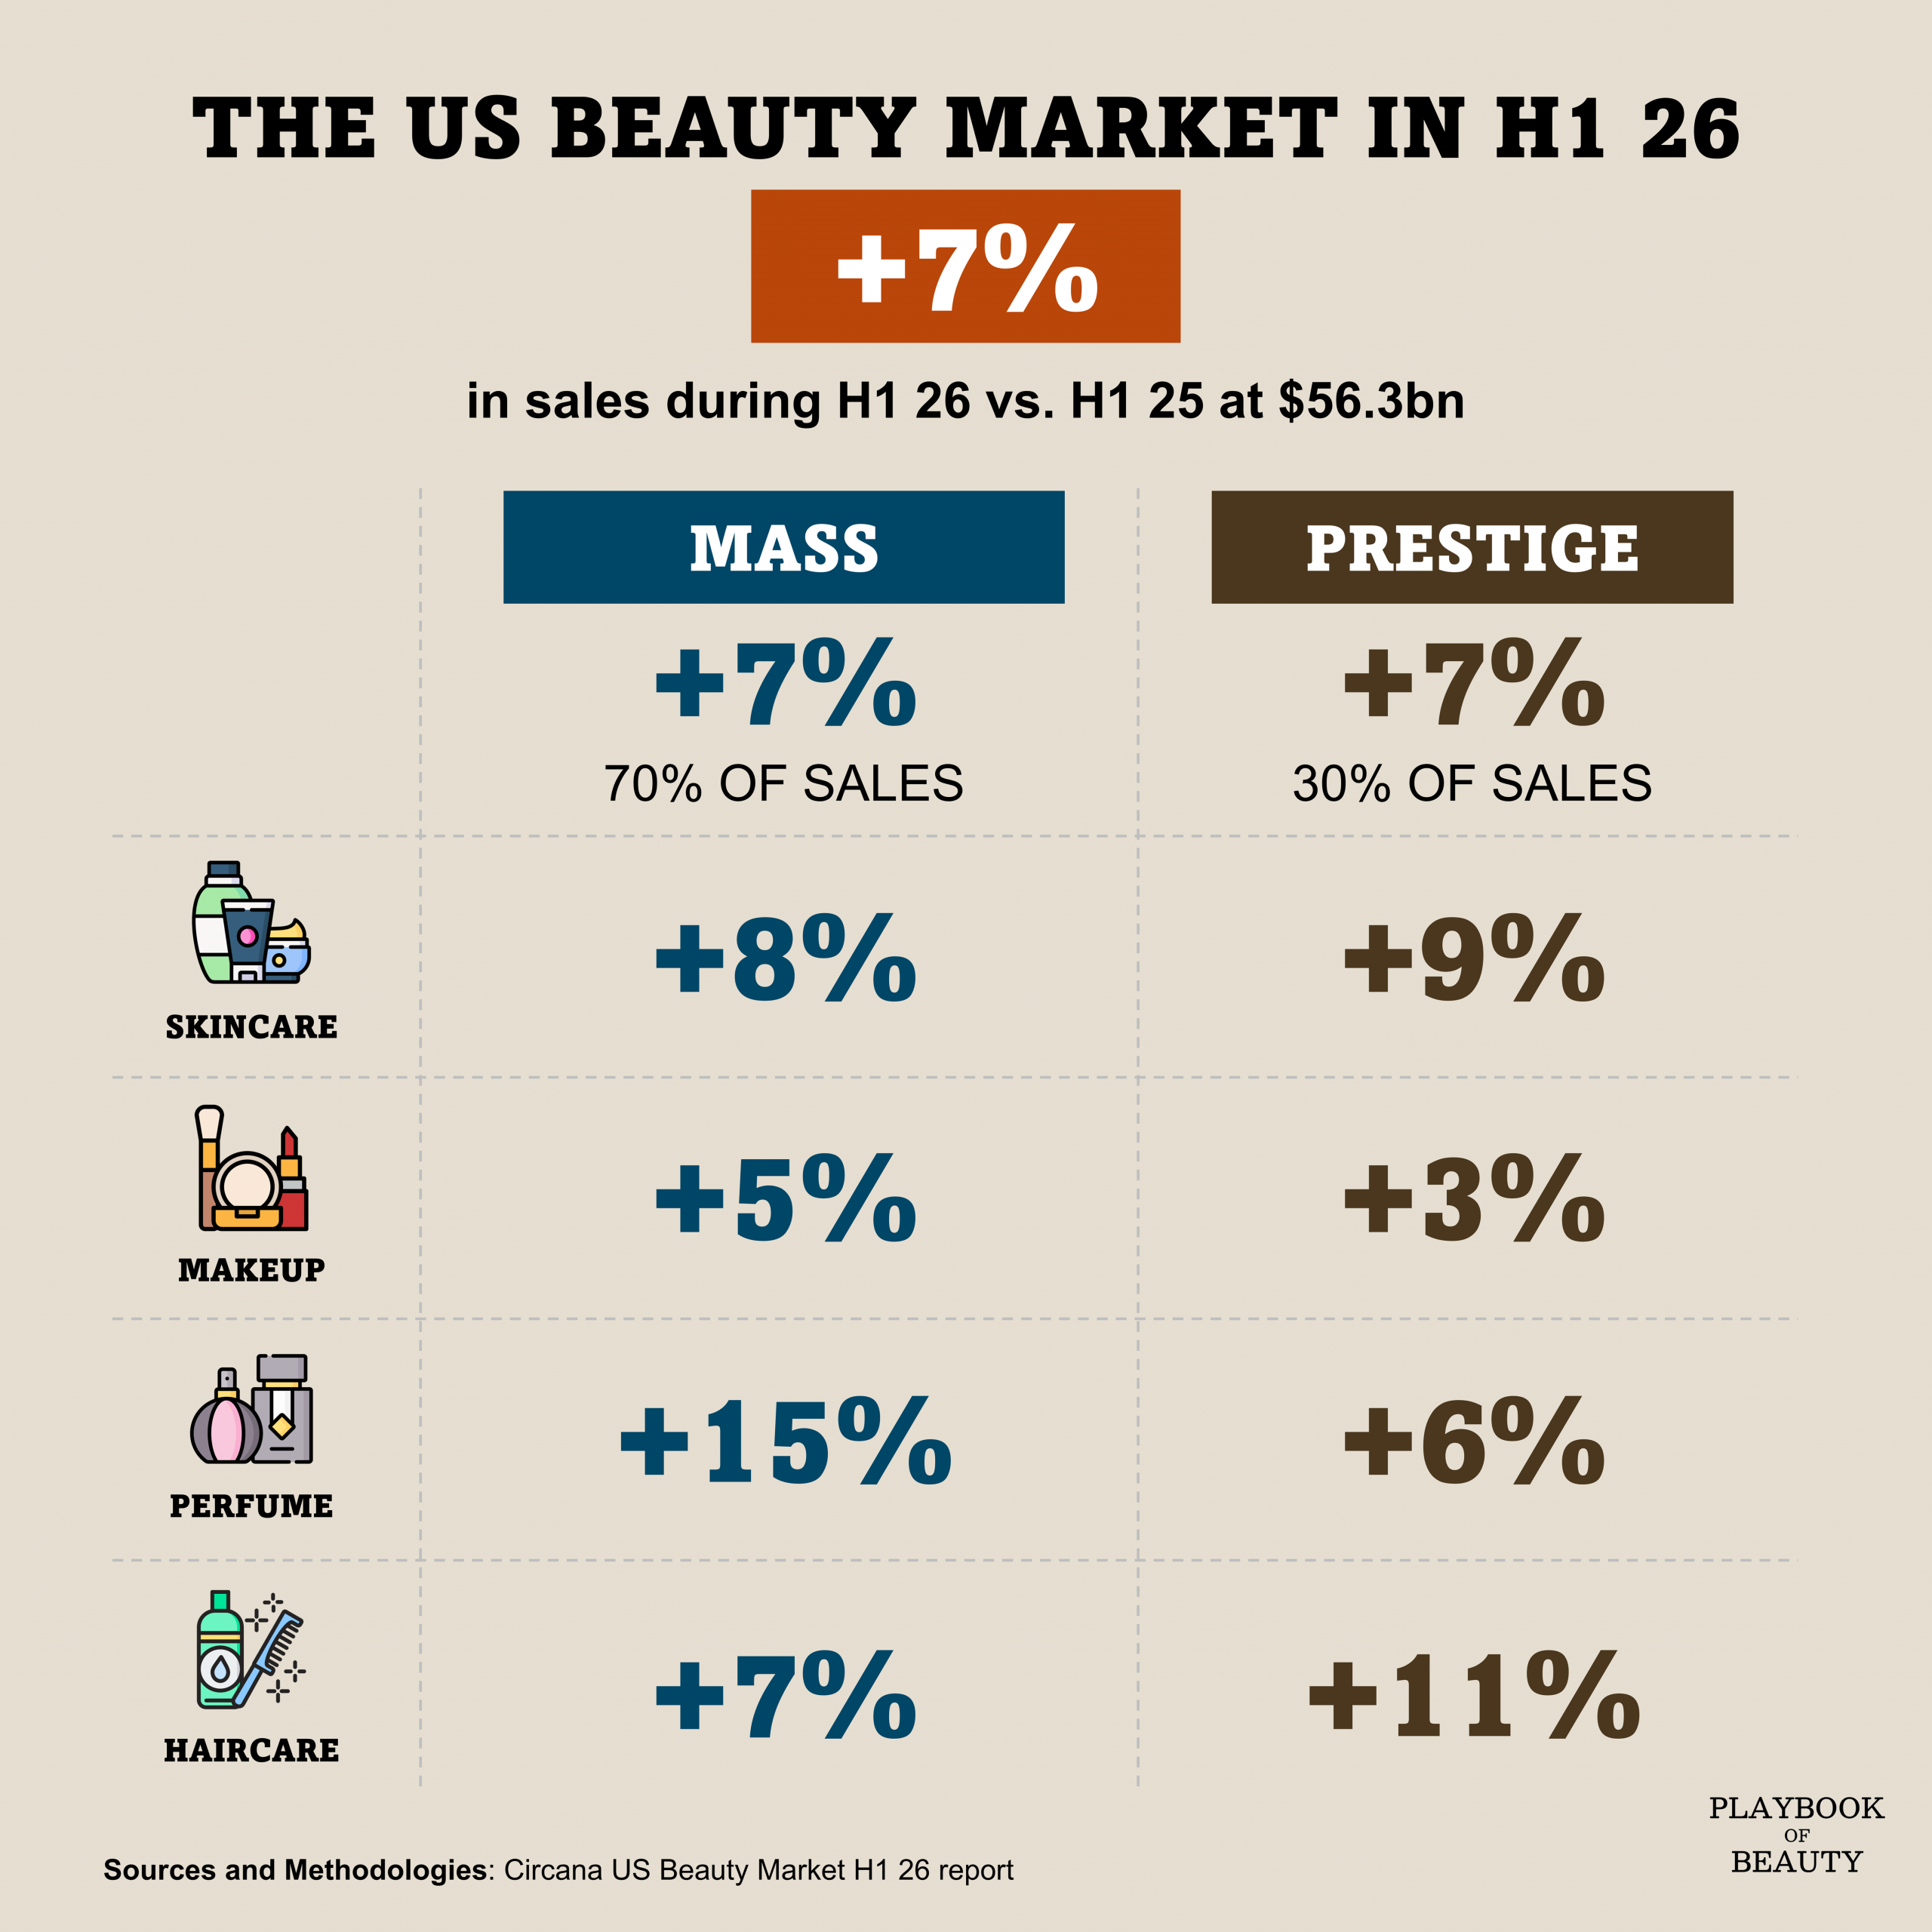
According to Circana, US beauty sales rose +7% in H1 2026 to $56.3bn, while in Canada prestige beauty sales grew at slightly lower +6% to $2.2bn.
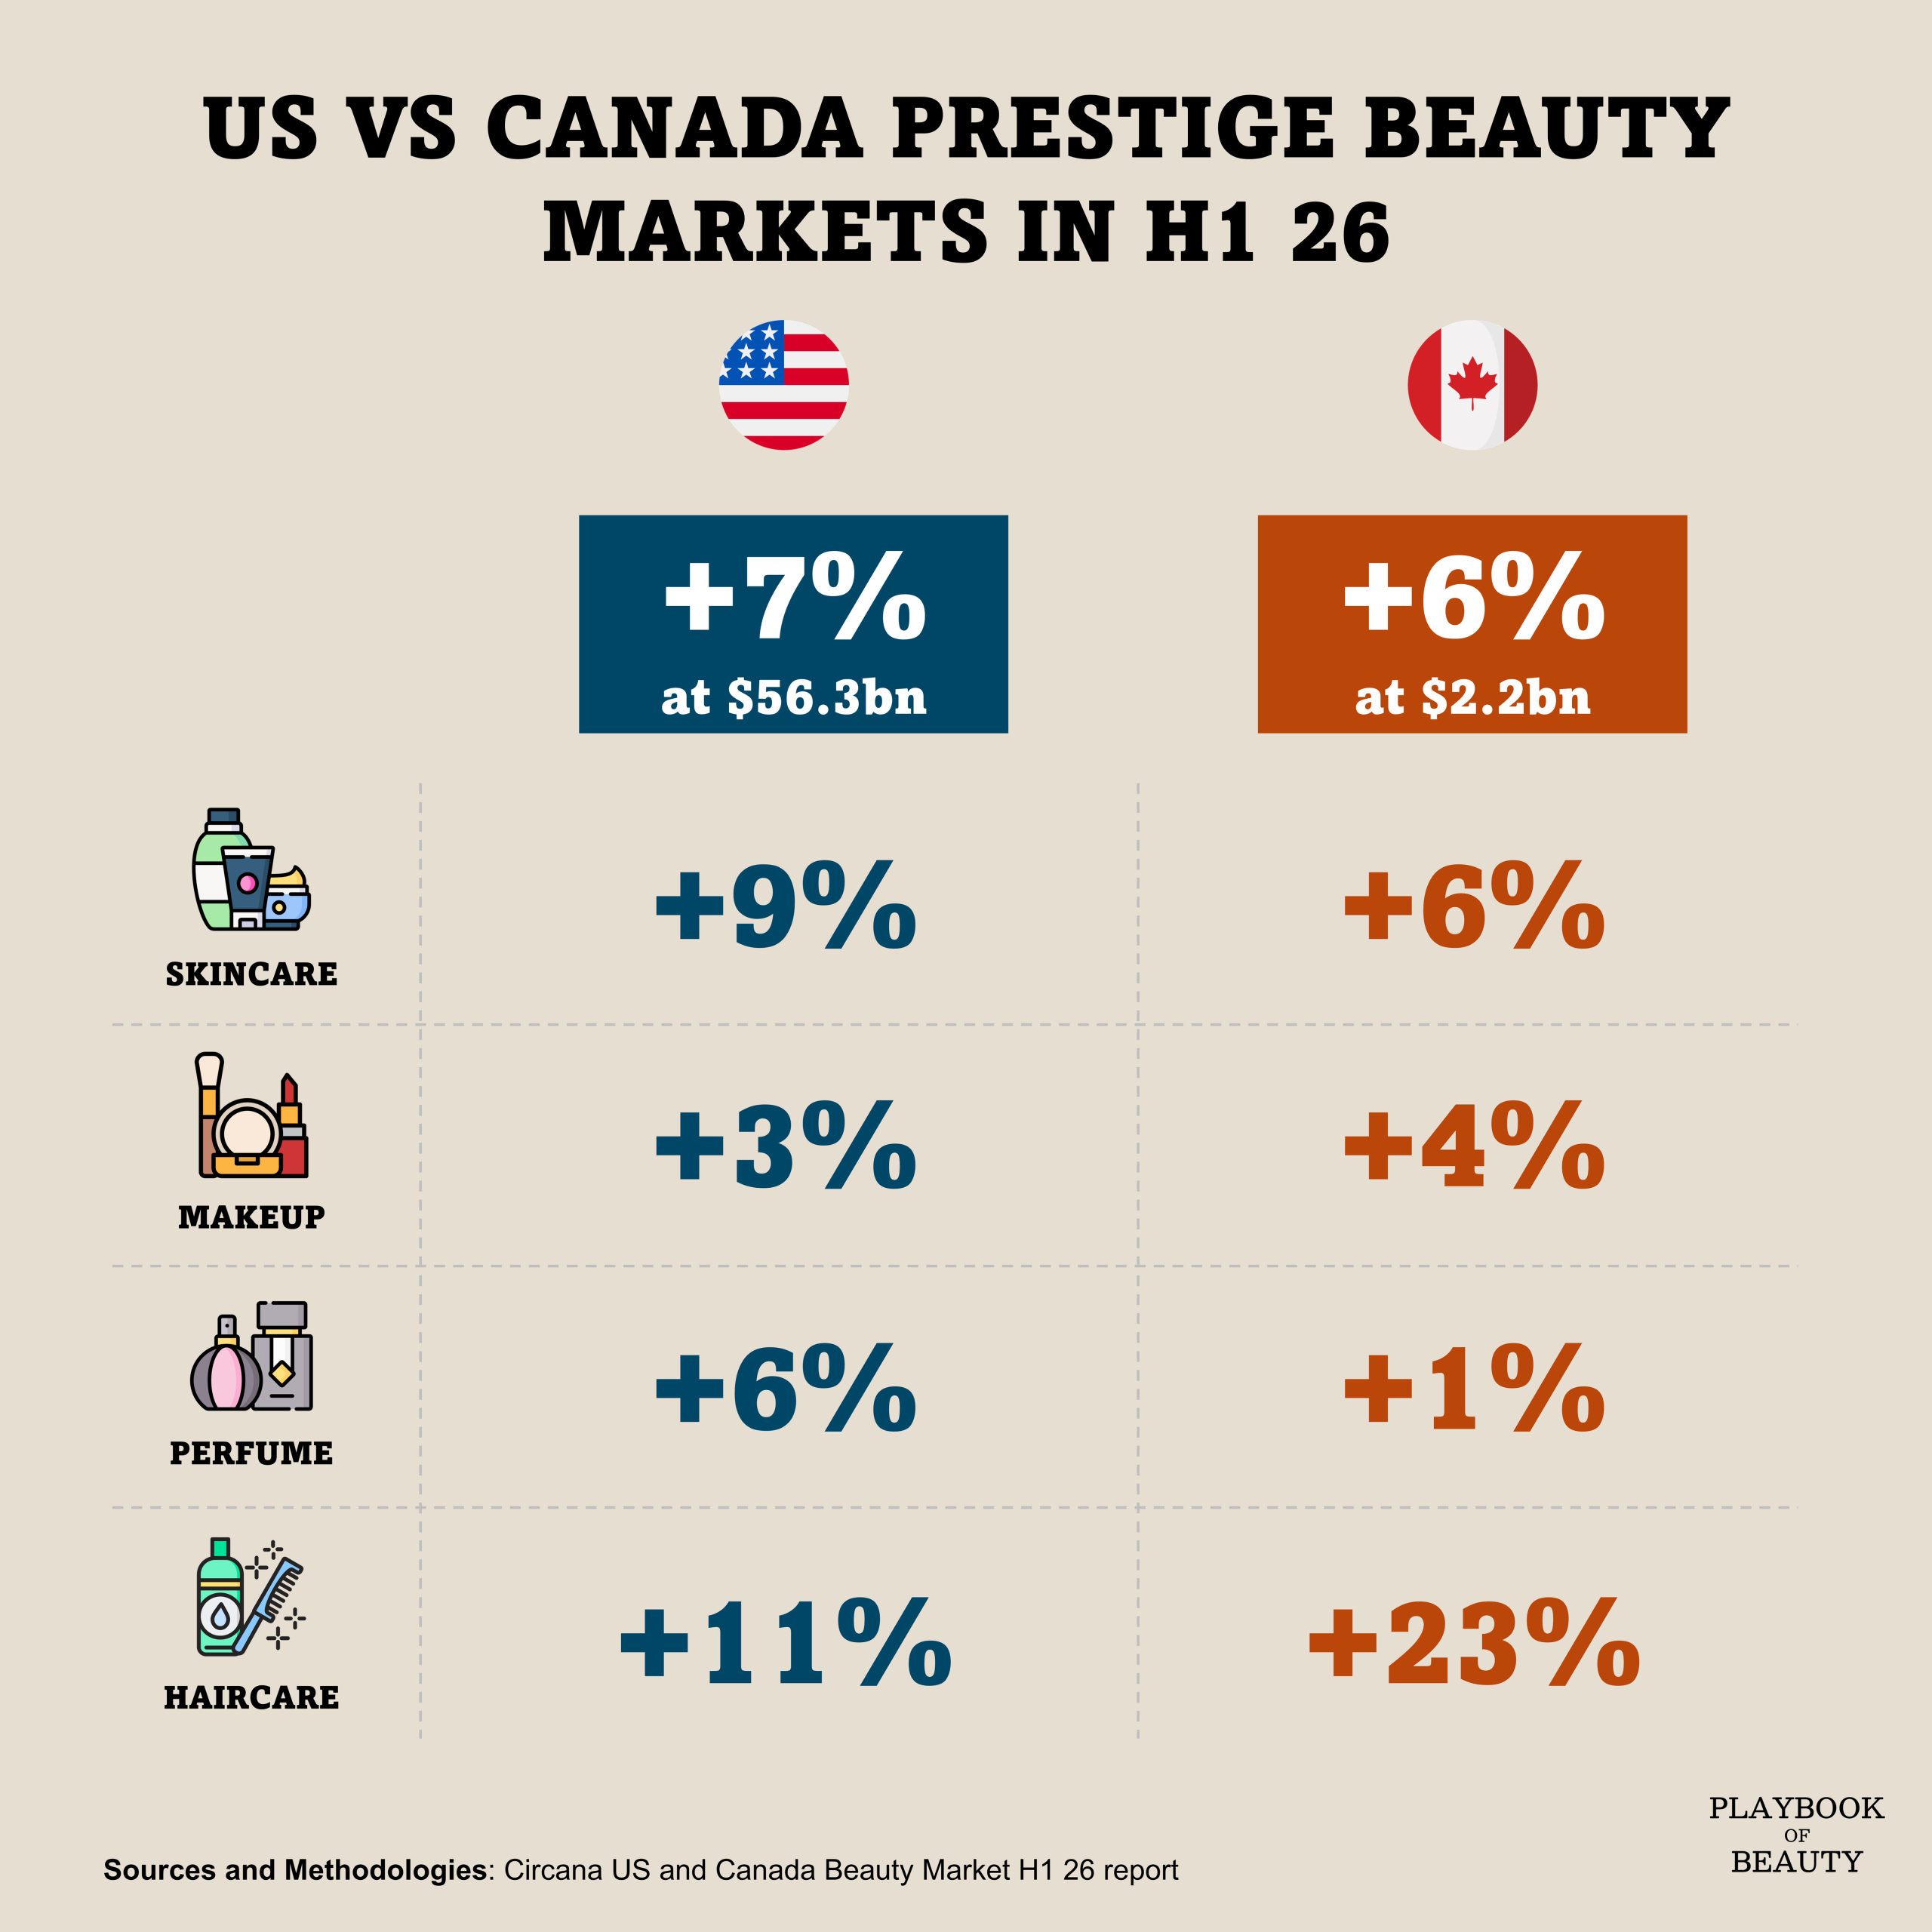
The rates are close but the comparison is more useful at category level. Haircare was the main growth engine in both countries, but Canada was much stronger. US prestige haircare grew +11% versus +23% in Canada. The gap reflects a stronger focus on scalp health, treatment routines and hair wellness in Canada, where hair serum grew +91%, daily rinse shampoo +22% and conditioner +20%.
Perfume was the second-fastest-growing category in the US, but the slowest in Canada at just +1%. US growth was supported by premium formats and higher prices. Canadian consumers remained engaged with fragrance, but growth shifted towards more concentrated products, body oils and scent-layering rituals rather than broad category expansion.
Skincare grew +9% in the US and +6% in Canada. Both markets are rewarding efficacy, clinical credibility and proven results. In Canada, mid-priced facial skincare showing how consumers are balancing performance with value while in the US, body care and suncare added to the facial skincare base.
Makeup was slower in both markets, growing +3% in the US and +4% in Canada. US growth was supported by social media, e-commerce and innovation in formats and functionality while in Canada, online sales generated more than three-quarters of the category’s dollar gains.
In both countries consumers are still buying prestige beauty, but the strongest demand is going to products with a clear functional promise, wellness benefit or accessible form of indulgence. The difference is where that demand is concentrated: haircare in Canada, and a broader mix of categories in the US.