L’Oréal reported Q3 26 sales of €11.56bn, up 11.9% as reported. LFL growth was 7.2%, or 7.7% after adjusting for the timing of its IT transformation. Nine-month sales reached €35.34bn, up 6.9% on both LFL and adjusted bases.
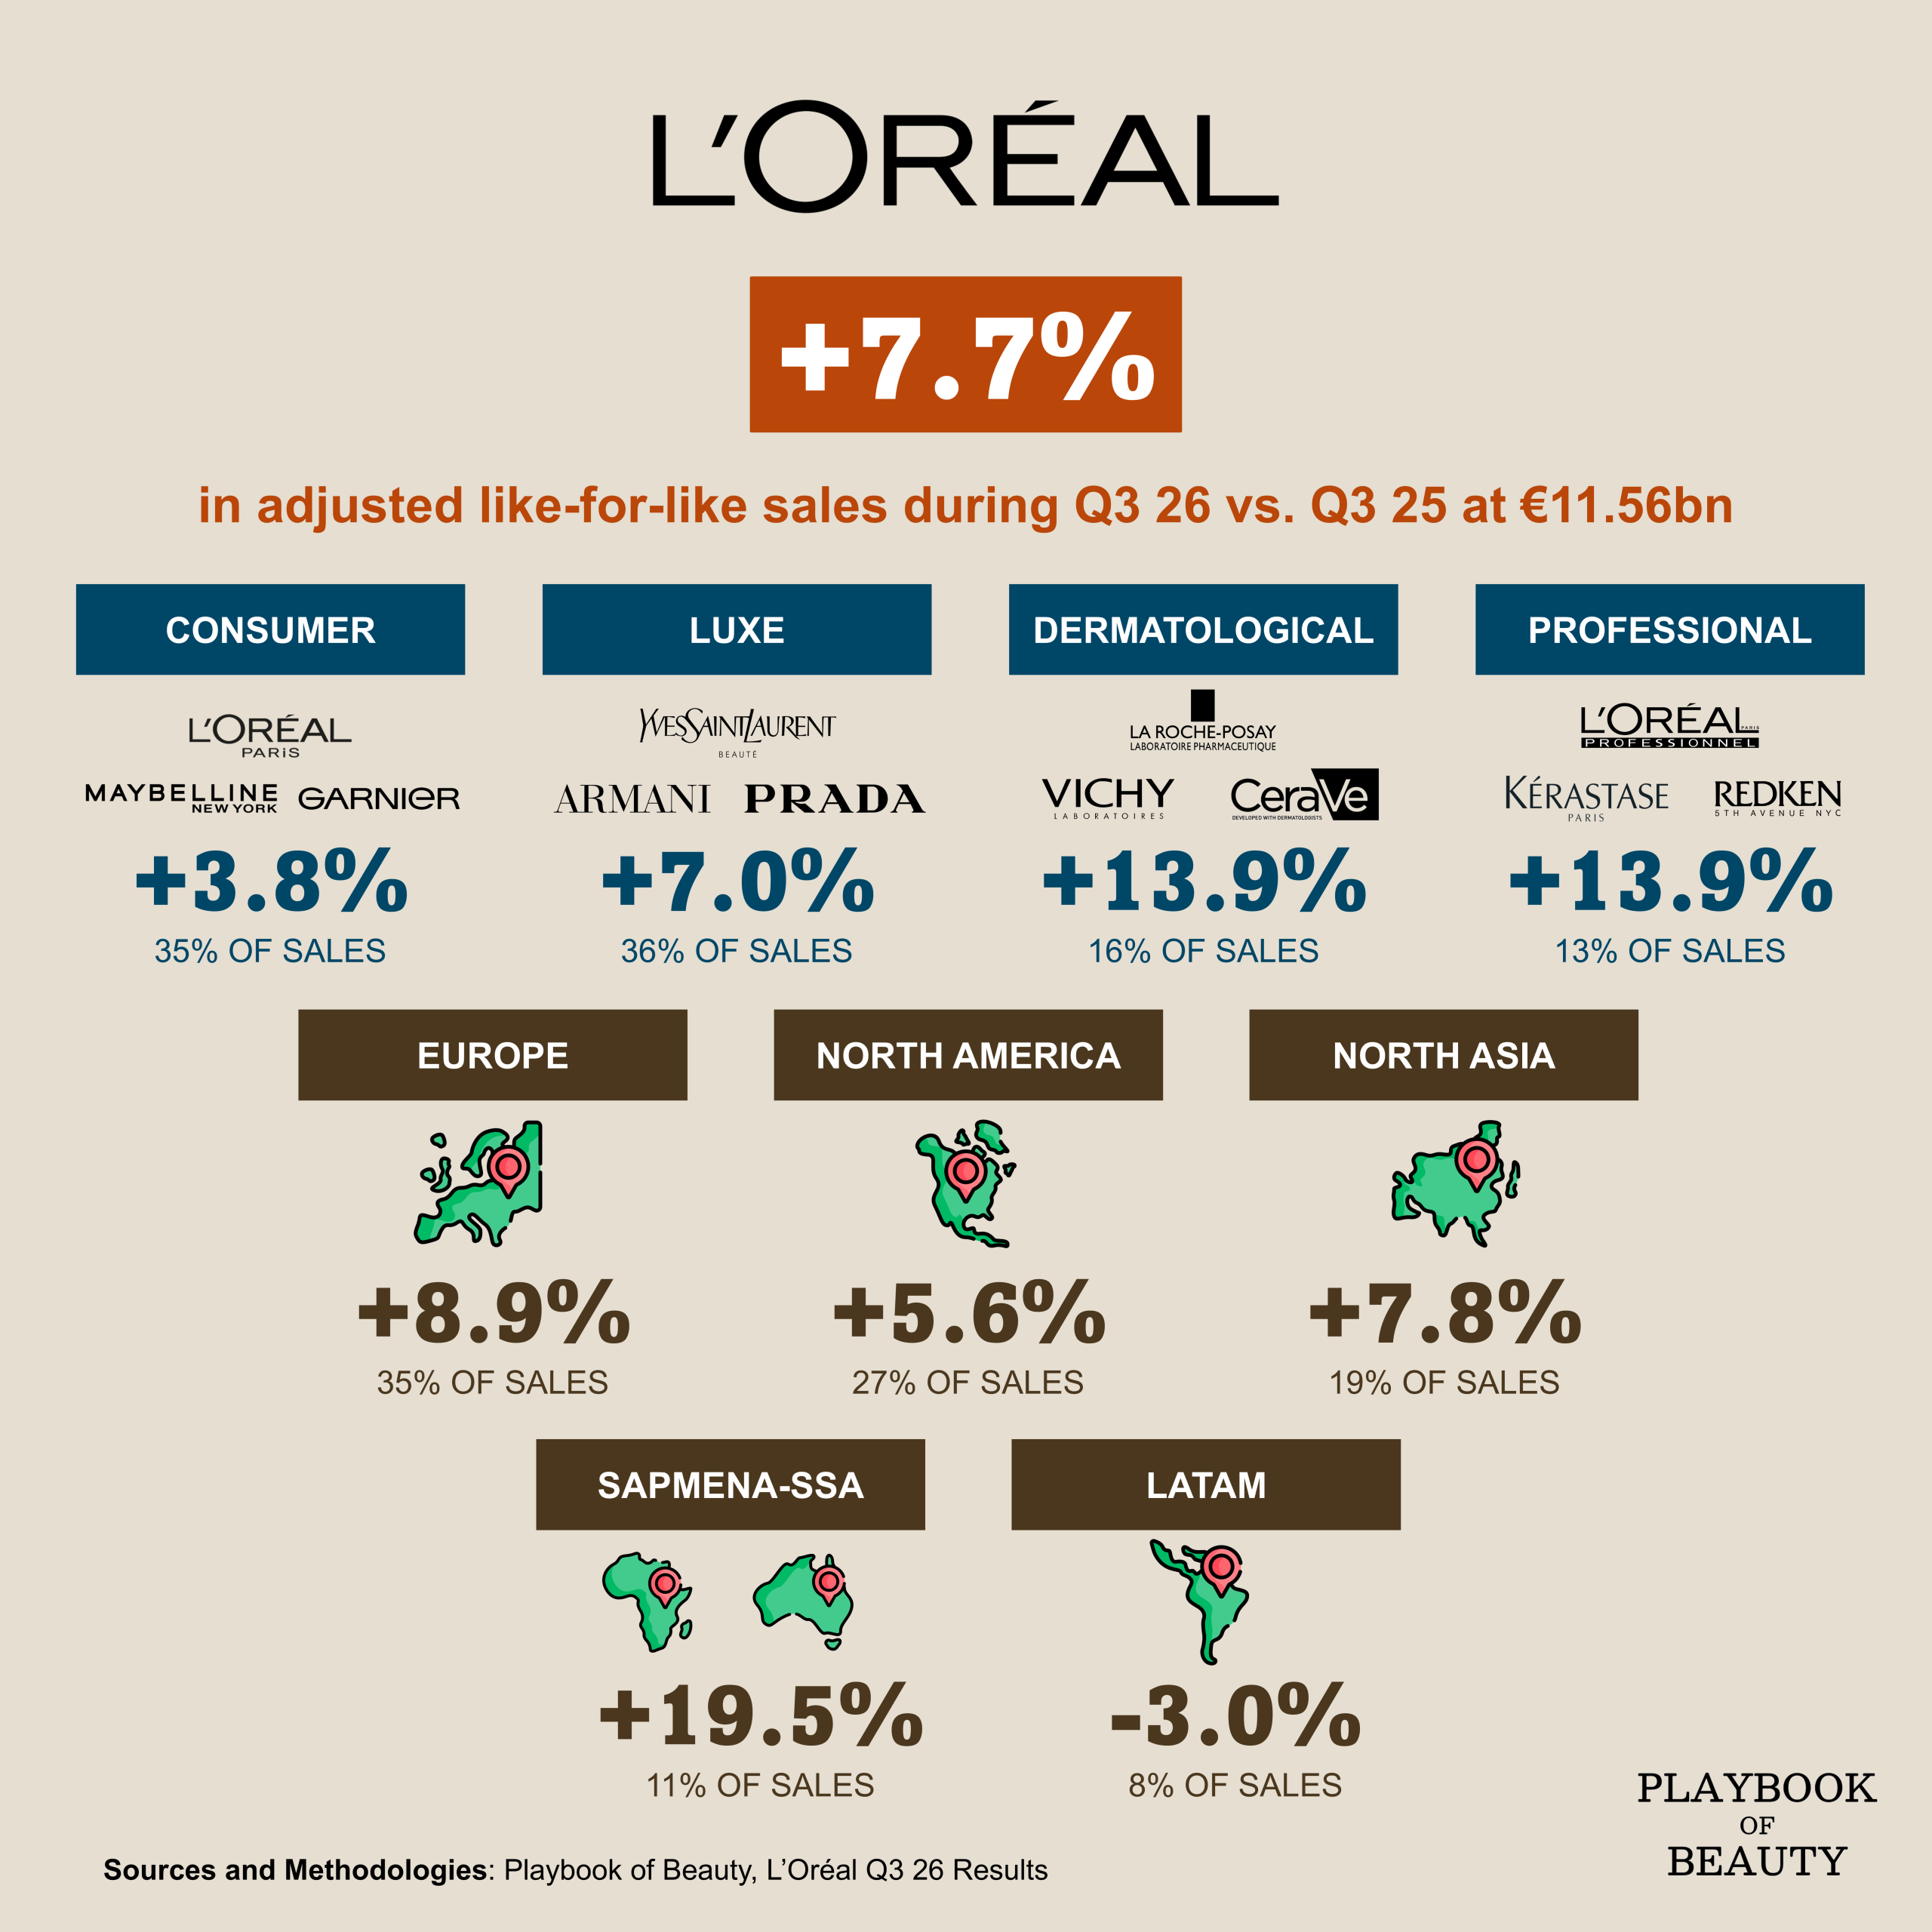
All four divisions grew in Q3 on an adjusted LFL basis. Professional Products and Dermatological Beauty led at 13.9% each, followed by Luxe at 7.0% and Consumer Products at 3.8%. The group’s adjusted growth accelerated from 6.5% in H1 to 7.7% in Q3.
Professional Products’ nine-month growth was supported by premium haircare, omnichannel distribution and salon services. Kérastase grew at a double-digit rate while Redken and L’Oréal Professionnel also contributed. Growth was balanced across all zones.
Dermatological Beauty grew 13.9% in Q3 and 11.6% over nine months. La Roche-Posay, CeraVe and SkinCeuticals each grew at double-digit rates over nine months driven by new La Roche-Posay and CeraVe Sun launches, and continued momentum at Vichy’s Dercos haircare brand.
Luxe accelerated in Q3, growing 7.0% on an adjusted LFL basis. Fragrance remained its main growth driver, with YSL Libre and MYSLF growing at double-digit rates but skincare also gained momentum. China posted double-digit growth over nine months.
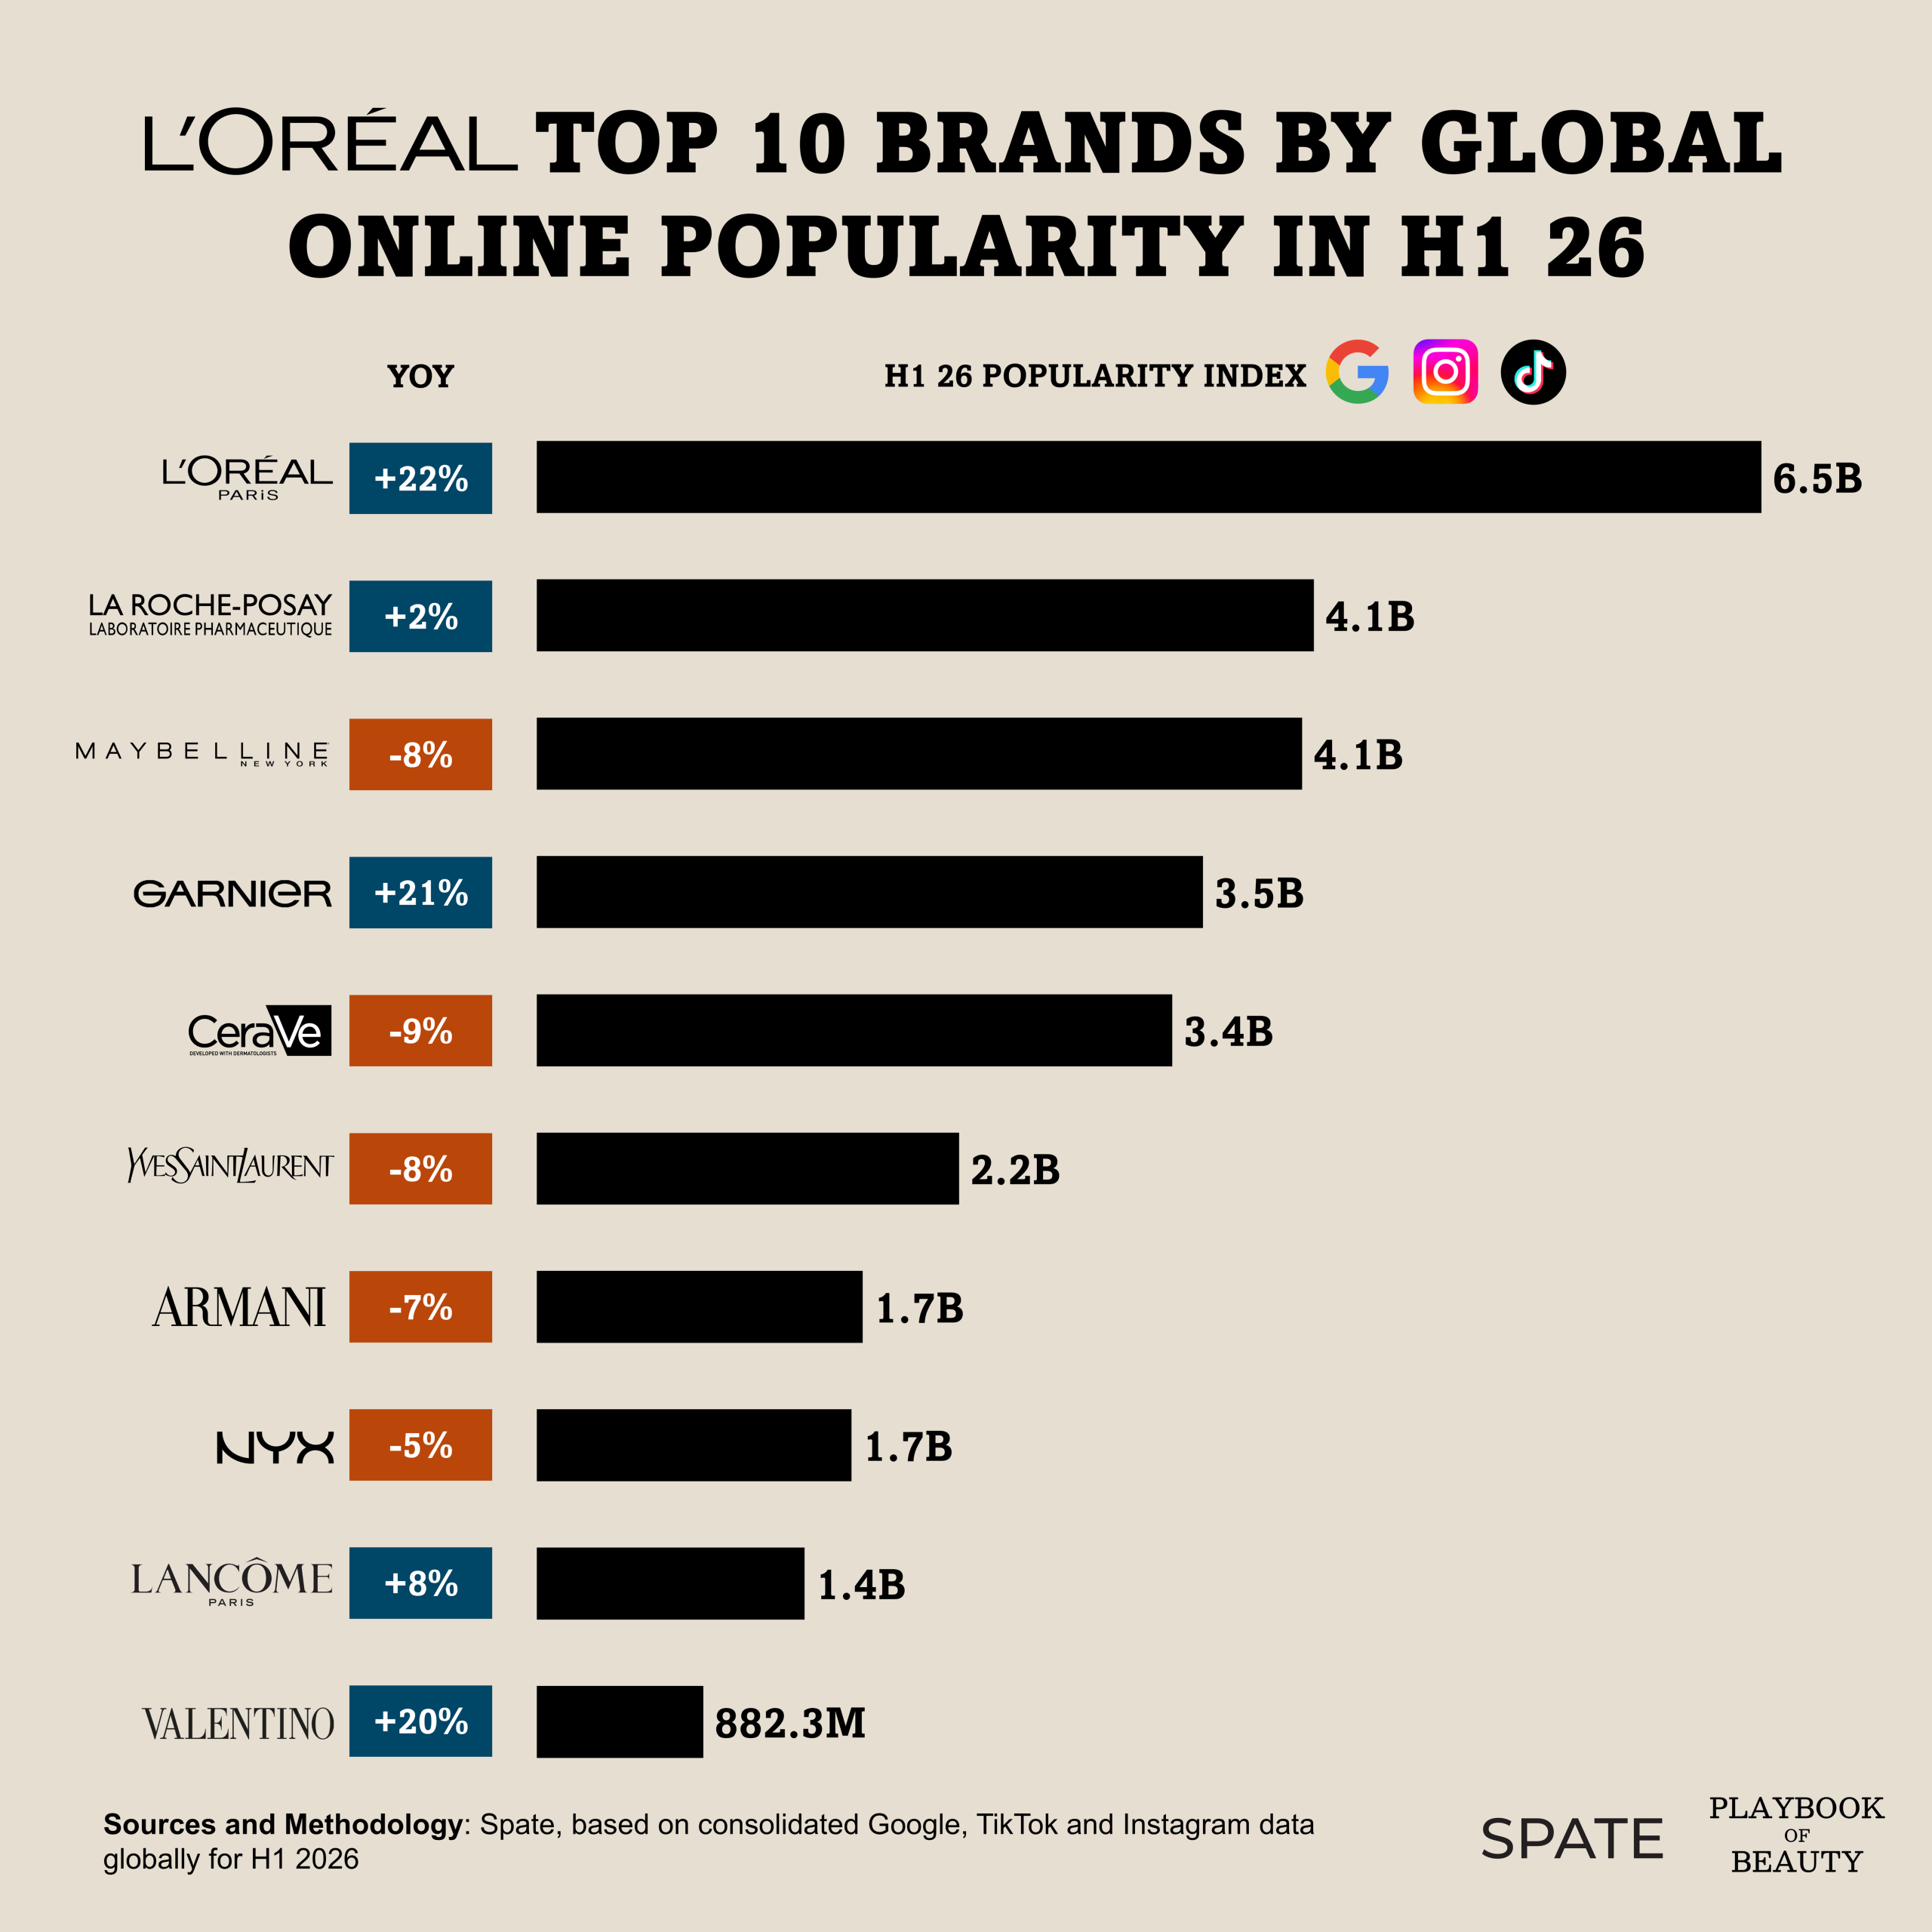
Consumer Products grew 3.8% in Q3 as volume growth accelerated. Over nine months, all global brands grew, particularly L’Oréal Paris and NYX Professional Makeup. Haircare grew at a double-digit rate, while Mixa expanded into new markets and Thayers grew in the United States.
By geography, SAPMENA-SSA led Q3 at 19.5% adjusted growth, followed by Europe at 8.9%, North Asia at 7.8% and North America at 5.6%. Latin America declined 3.0% on the same basis, with temporary makeup supply disruptions and distributor stock adjustments in Mexico. Group e-commerce grew around 17% over nine months.
Subscribe to my newsletter for weekly insights on the beauty industry. Link in the comments