According to data from , an e-commerce intelligence platform that helps brands monitor and benchmark their online search visibility and retail media, Dior was the brand with the highest overall organic share of voice across 42 retailers in 16 countries. However, when focusing on mature Western markets, the picture is more nuanced: Dior leads in Germany at 17.2% and Italy at 7.8%, while Yves Saint Laurent leads in the USA (10.2%), Spain (4.3%) and the UK (5.4%).Yves Saint Laurent is the only brand appearing in the top 10 in all six countries, and ranks in the top 4 everywhere. Dior and Chanel both appear in five out of six markets, as does Armani. Prada and Jean Paul Gaultier also show strong cross-market visibility.
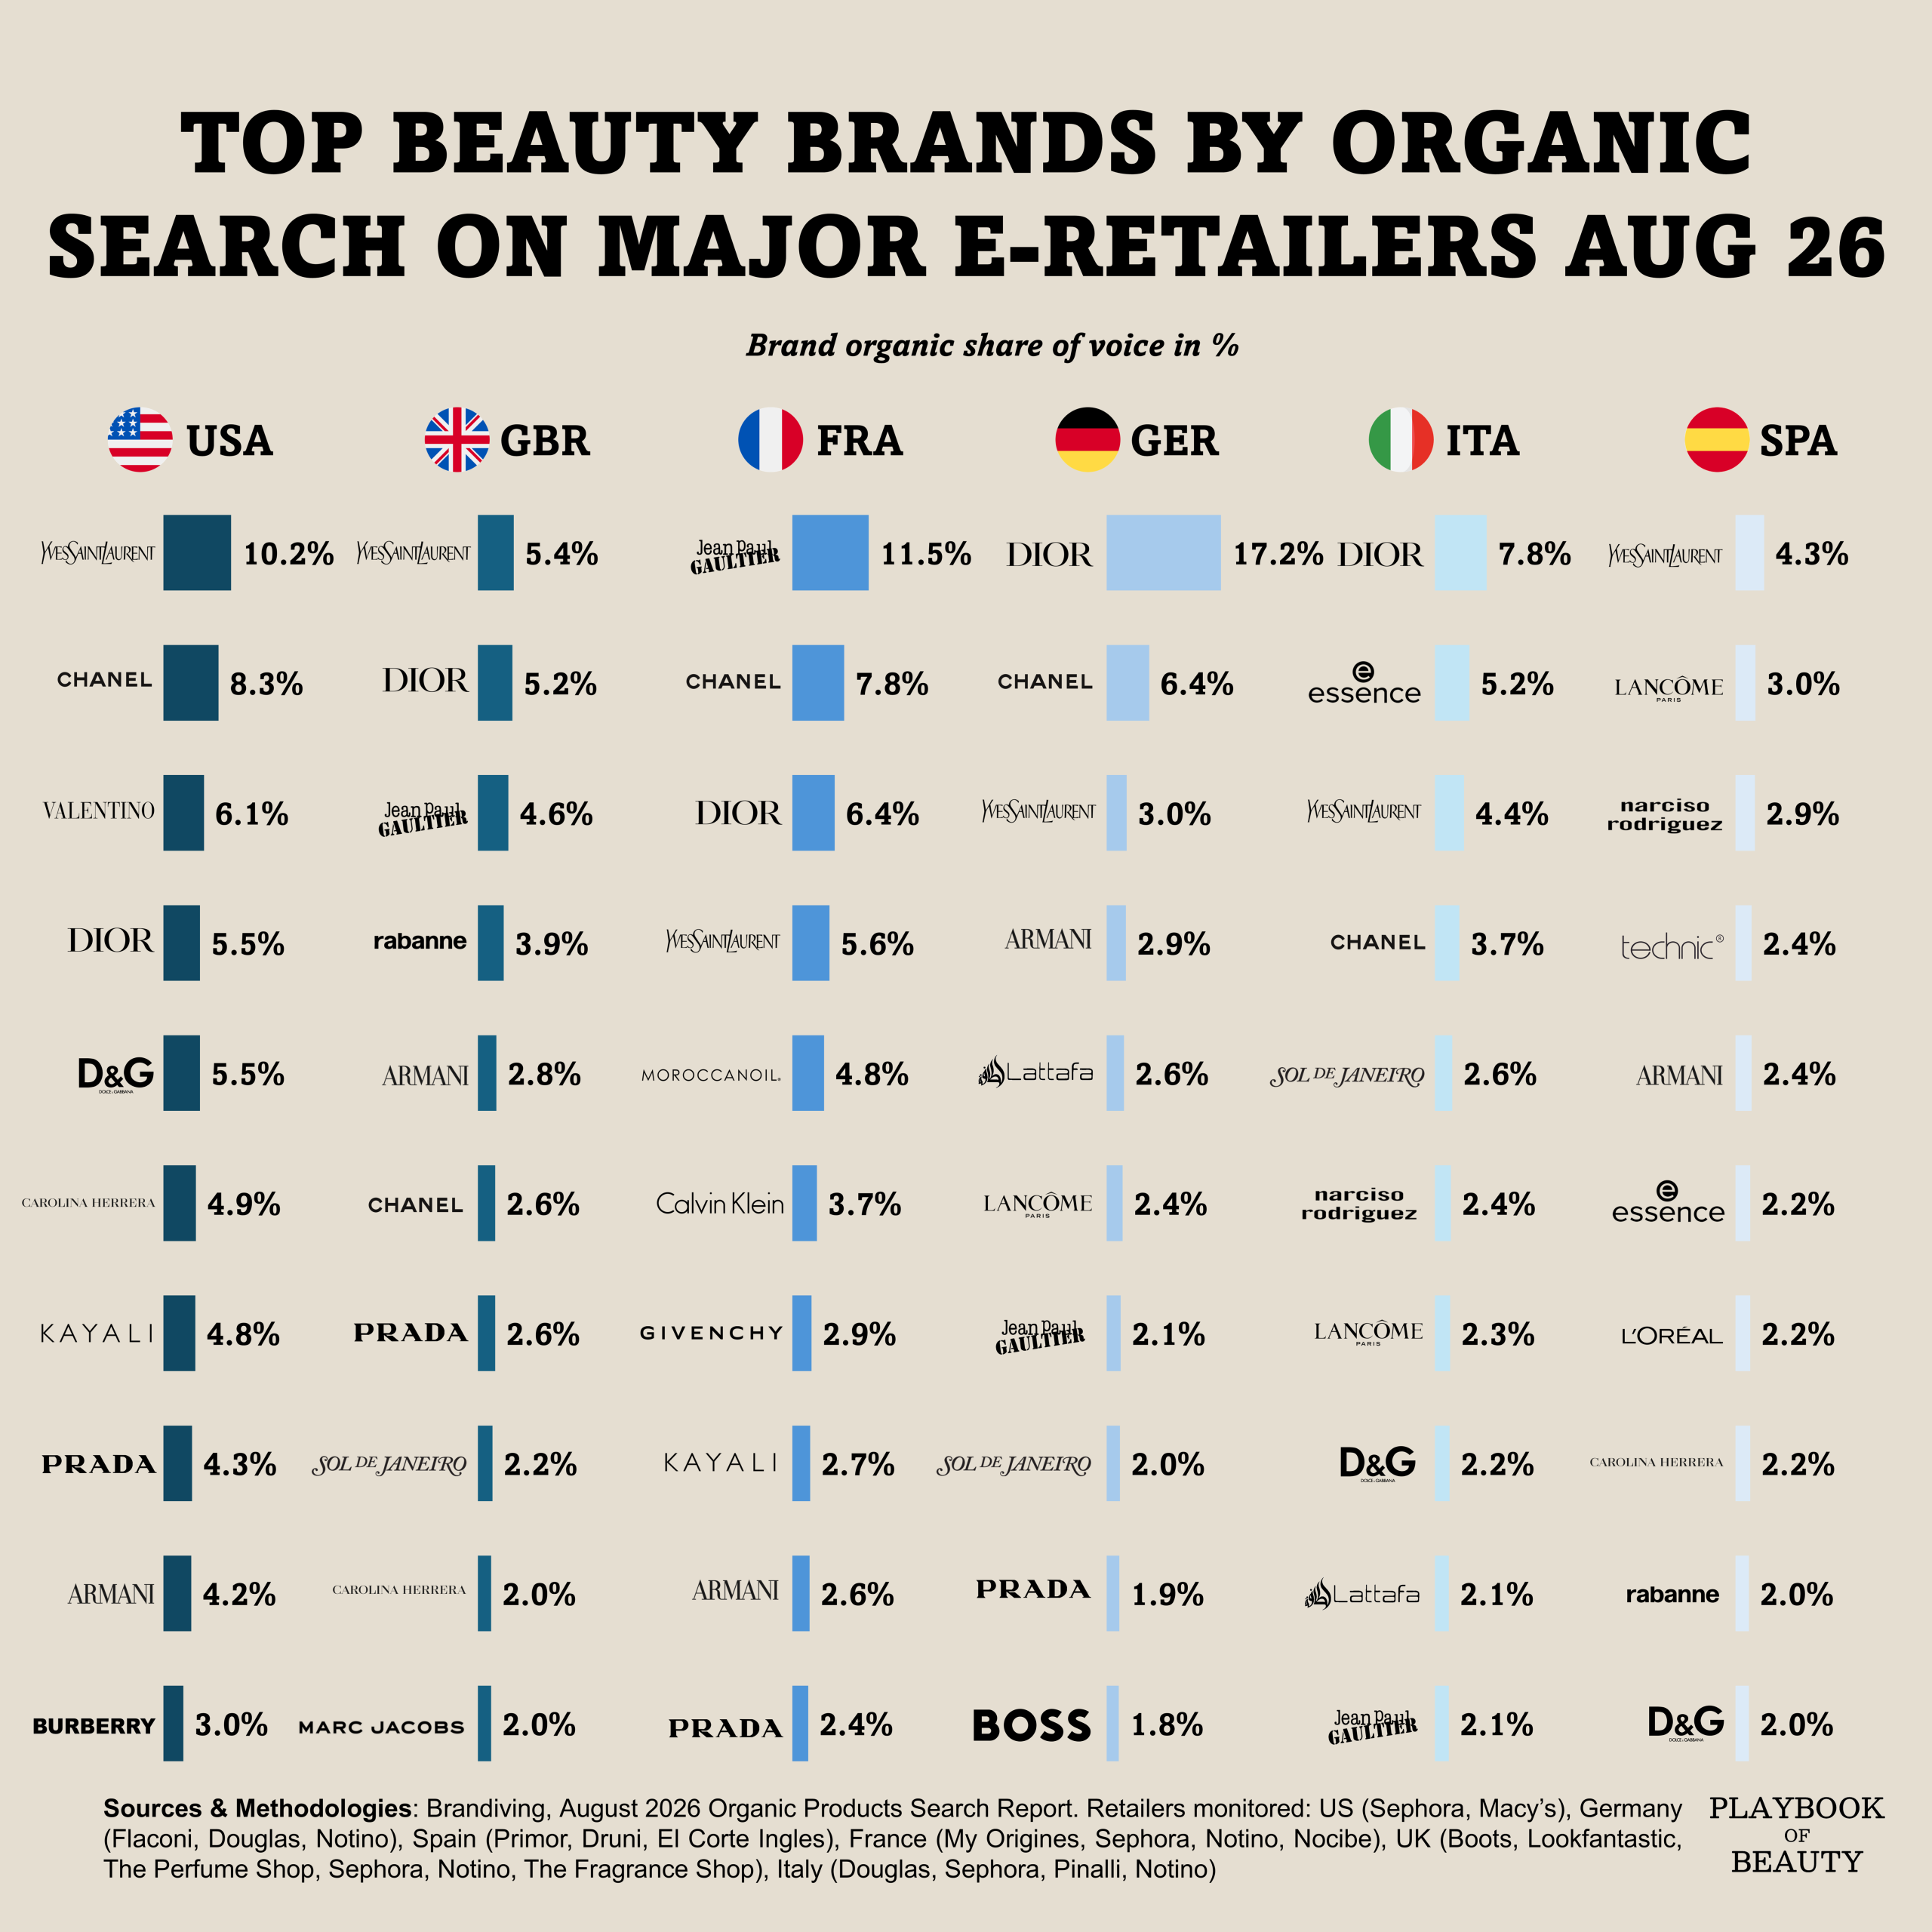
But there are also interesting local winners. Jean Paul Gaultier reaches #1 in France with 11.5%, Essence #2 in Italy with 5.2%, Valentino #3 in the US with 6.1%, while Middle Eastern fragrance brands Lattafa and Kayali manage to break into the US, France, Italy and Germany.
When looking at the brand mix, Spain is the clearest outlier. While the US, France, Germany and the UK Top 10s are almost entirely made up of prestige and luxury brands, Spain includes mass-market players such as Technic, Essence and L’Oréal Paris. Italy sits somewhere in between, with Essence ranking #2 alongside Dior, YSL and Chanel while Germany, by contrast, is particularly luxury and fragrance-driven.
Beyond the brand themselves, the biggest difference between those market is how concentrated organic search visibility is.
The Top 10 brands account for 56.8% of organic share of voice in the US and 50.4% in France, compared with 42.3% in Germany, 34.8% in Italy, 33.3% in the UK and only 25.6% in Spain. Germany is also unusually top-heavy, with Dior alone capturing 17.2%, while Spain’s top brand reaches just 4.3%.
So, while the names at the top are often similar, the competitive dynamics behind them are very different: some markets are dominated by a relatively small group of global prestige brands, while others offer a much more fragmented search landscape and more room for mass and challenger brands.