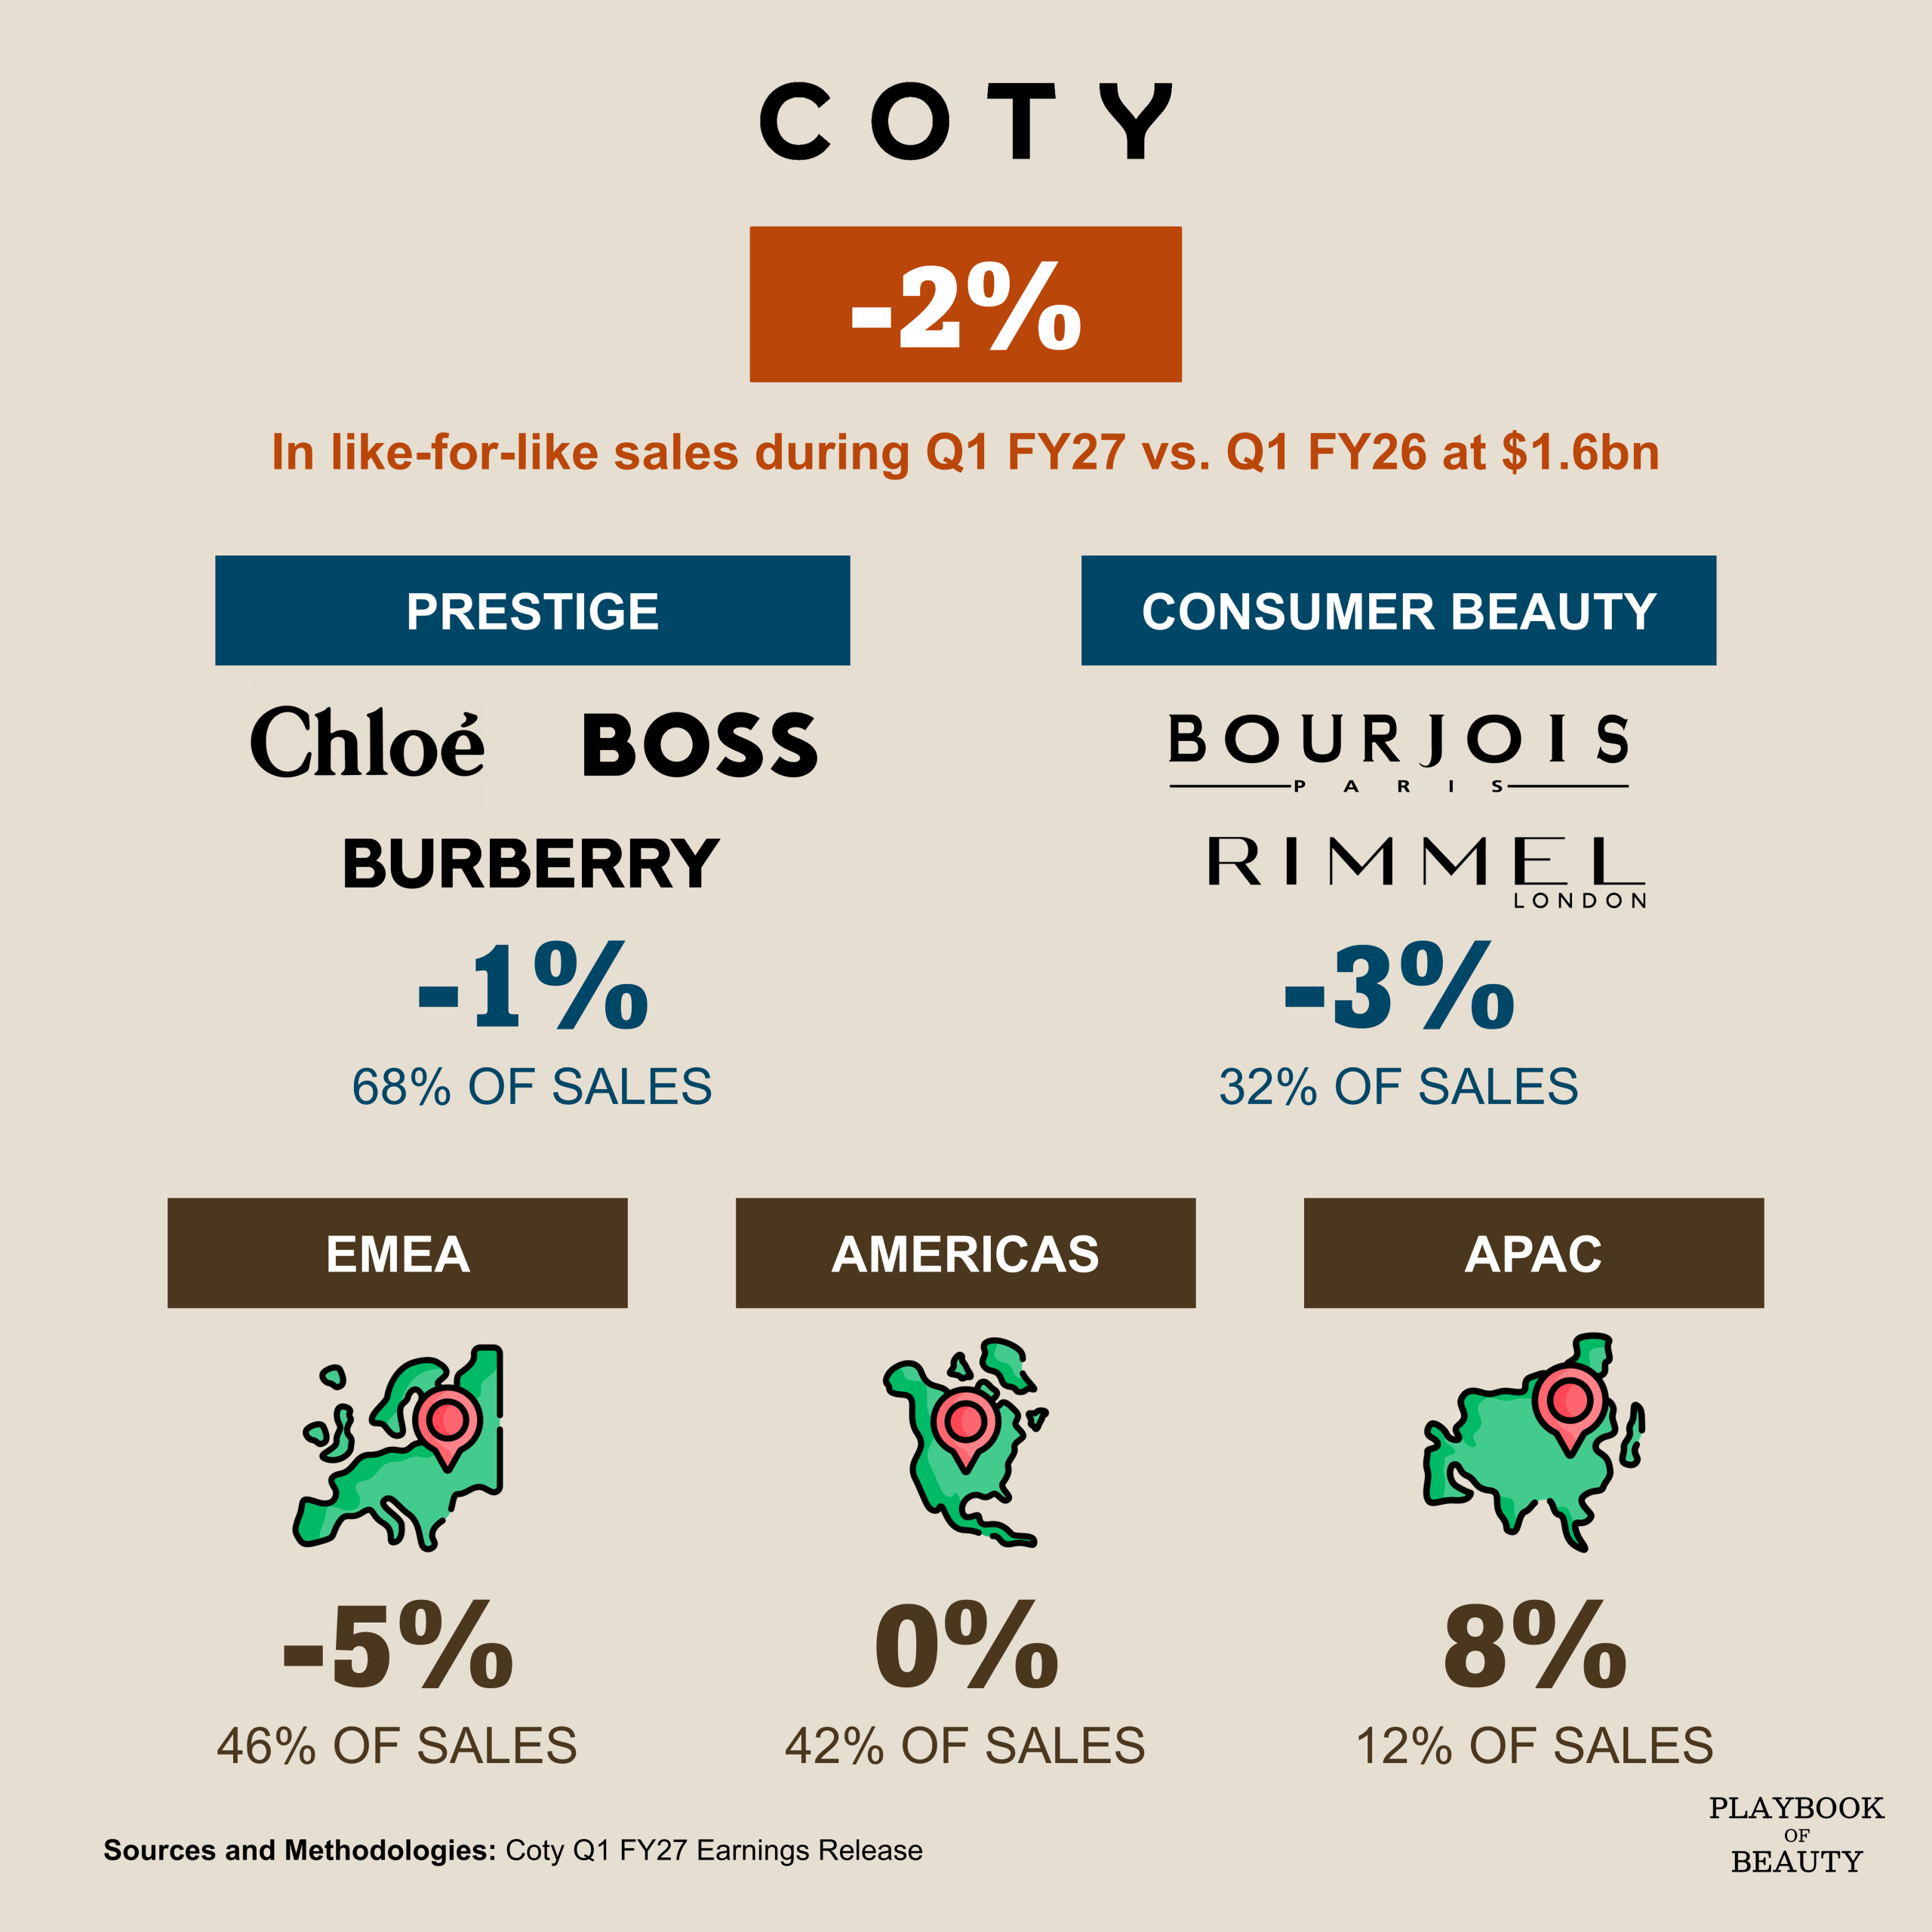
Coty ended Q1 FY27 with net revenue of $1.56bn, down 1% on a reported basis and 2% like-for-like. Adjusted operating income fell 8% to $220.5m and adjusted EBITDA fell 7% to $274.2m. Adjusted operating margin contracted 100 basis points to 14.2%. Adjusted net income rose 38% to $146.1m, including a $14.8m equity swap benefit versus a $26.5m negative impact a year ago. Cash flow from operations more than doubled to $130.4m, while free cash flow rose to $84.6m from $11.2m.
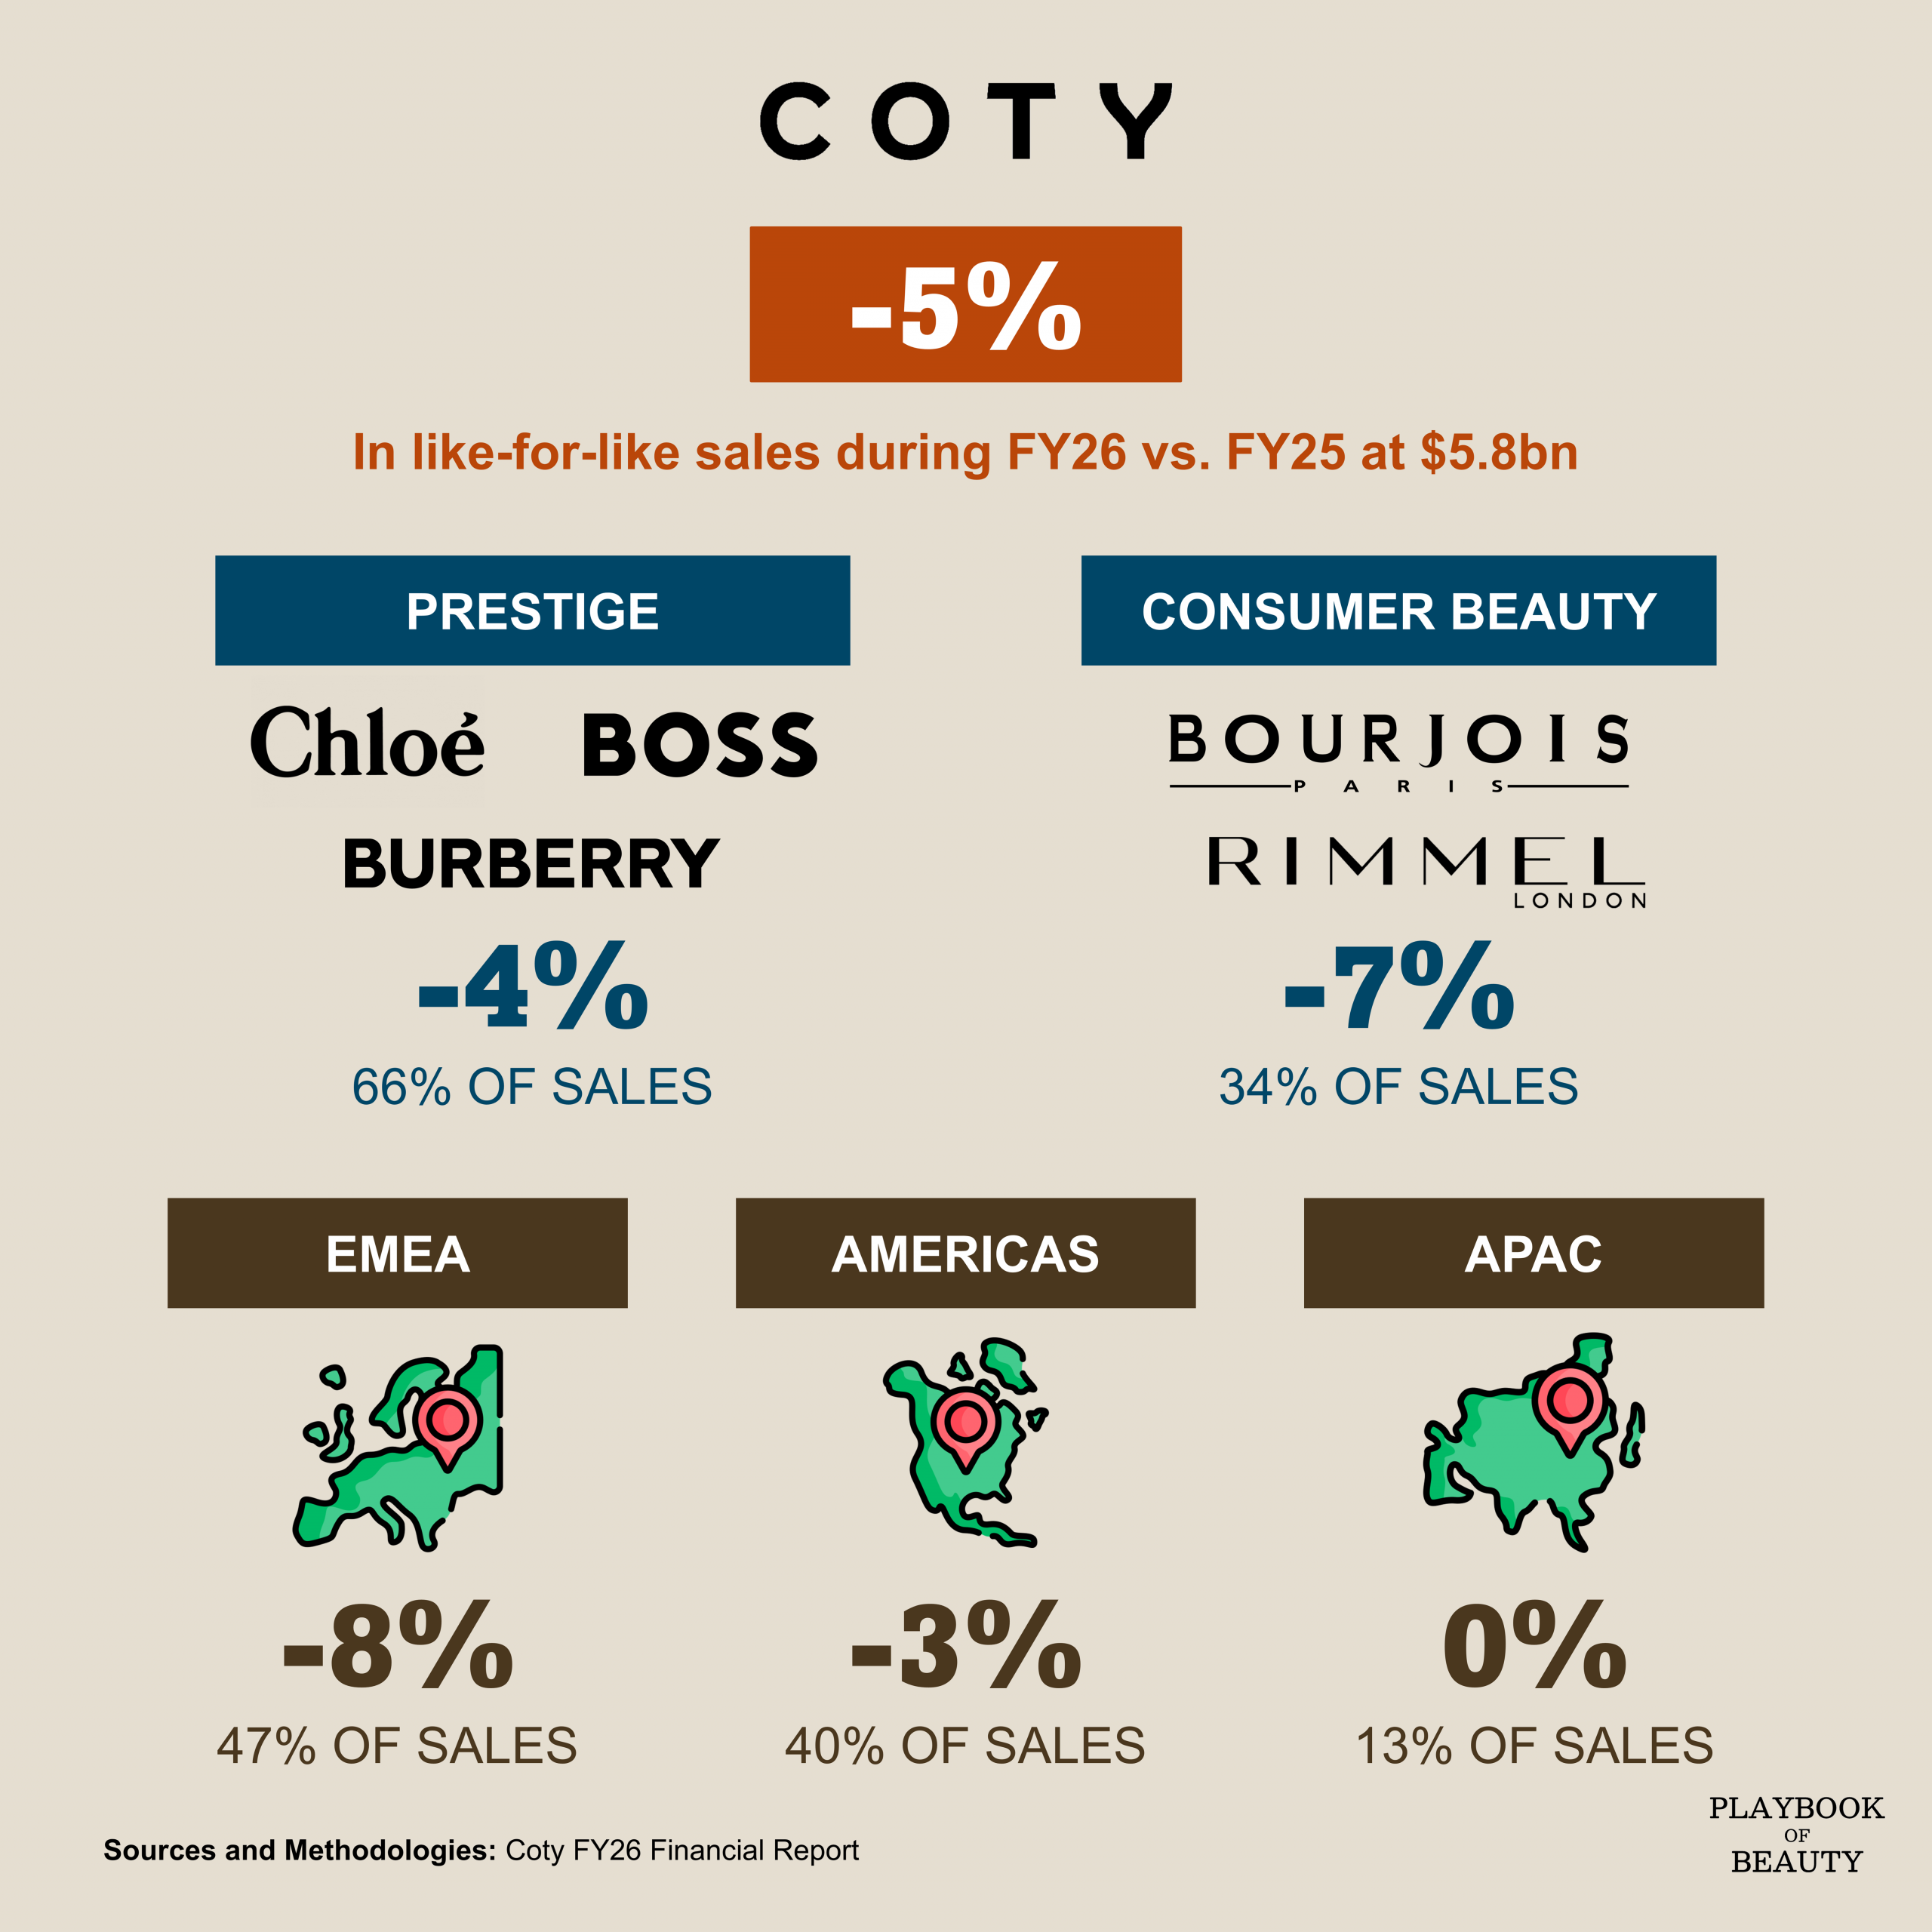
The like-for-like sales decline narrowed from 6% in the first half and 4% in the second half of FY26 to 2% in Q1. Still, Coty says sell-out continues to trail the market in both Prestige and Consumer Beauty. Gross margin fell 120 basis points to 63.3%, reflecting higher freight and material costs related to the Middle East conflict and higher excess and obsolescence costs.
Prestige generated sales of $1.06bn, or 68% of group sales, down 1% like-for-like. A moderate decline in fragrance and skincare was partly offset by growth in cosmetics. Coty’s Top 6 core Prestige brands grew 5% like-for-like, after declining 6% in the first half of FY26, with five of the six brands growing. First-half launches contributed approximately 2% to their growth. Prestige adjusted EBITDA fell 2% to $262.5m, with a 24.8% margin.
Consumer Beauty generated $496.8m, or 32% of sales, down 3% like-for-like. Declines in color cosmetics and mass fragrance were partly offset by growth in mass body care. CoverGirl and Sally Hansen in the U.S. and Rimmel in the U.K. narrowed their retail sales gaps to their categories. Sally Hansen regained the number-one position among U.S. mass nail brands. Adjusted EBITDA fell 59% to $11.7m, and the adjusted operating loss widened to $15.0m.
Regionally, the Americas generated $653m, or 42% of sales, and was flat like-for-like, with higher sales in Brazil. EMEA, Coty’s largest region at $710m, fell 5% like-for-like as lower sales in the Middle East and Europe were partly offset by Africa. Asia Pacific was $192m, or 12% of sales, up 8% like-for-like, supported by China, Southeast Asia and Asia Travel Retail.
For Q2, Coty expects a low-single-digit like-for-like sales decline and a high-single-digit fall in adjusted EBITDA, with adjusted EPS excluding the equity swap of $0.16 to $0.18. The company still expects first-half FY27 free cash flow above $300m, but has not provided full-year FY27 guidance while its strategic review continues. Coty expects the review to conclude by the end of calendar 2026 and describes FY27 as a transition year.