Across 22 listed beauty businesses, revenue-weighted year-on-year growth increased to 6.1% in Q3 from 5.0% in Q2, a 1.1 percentage point improvement. 15 groups grew over the quarter (vs. 11 in Q2), 2 did not grow (vs. 3 in Q2) and 5 saw their sales decrease (vs. 8 in Q2).
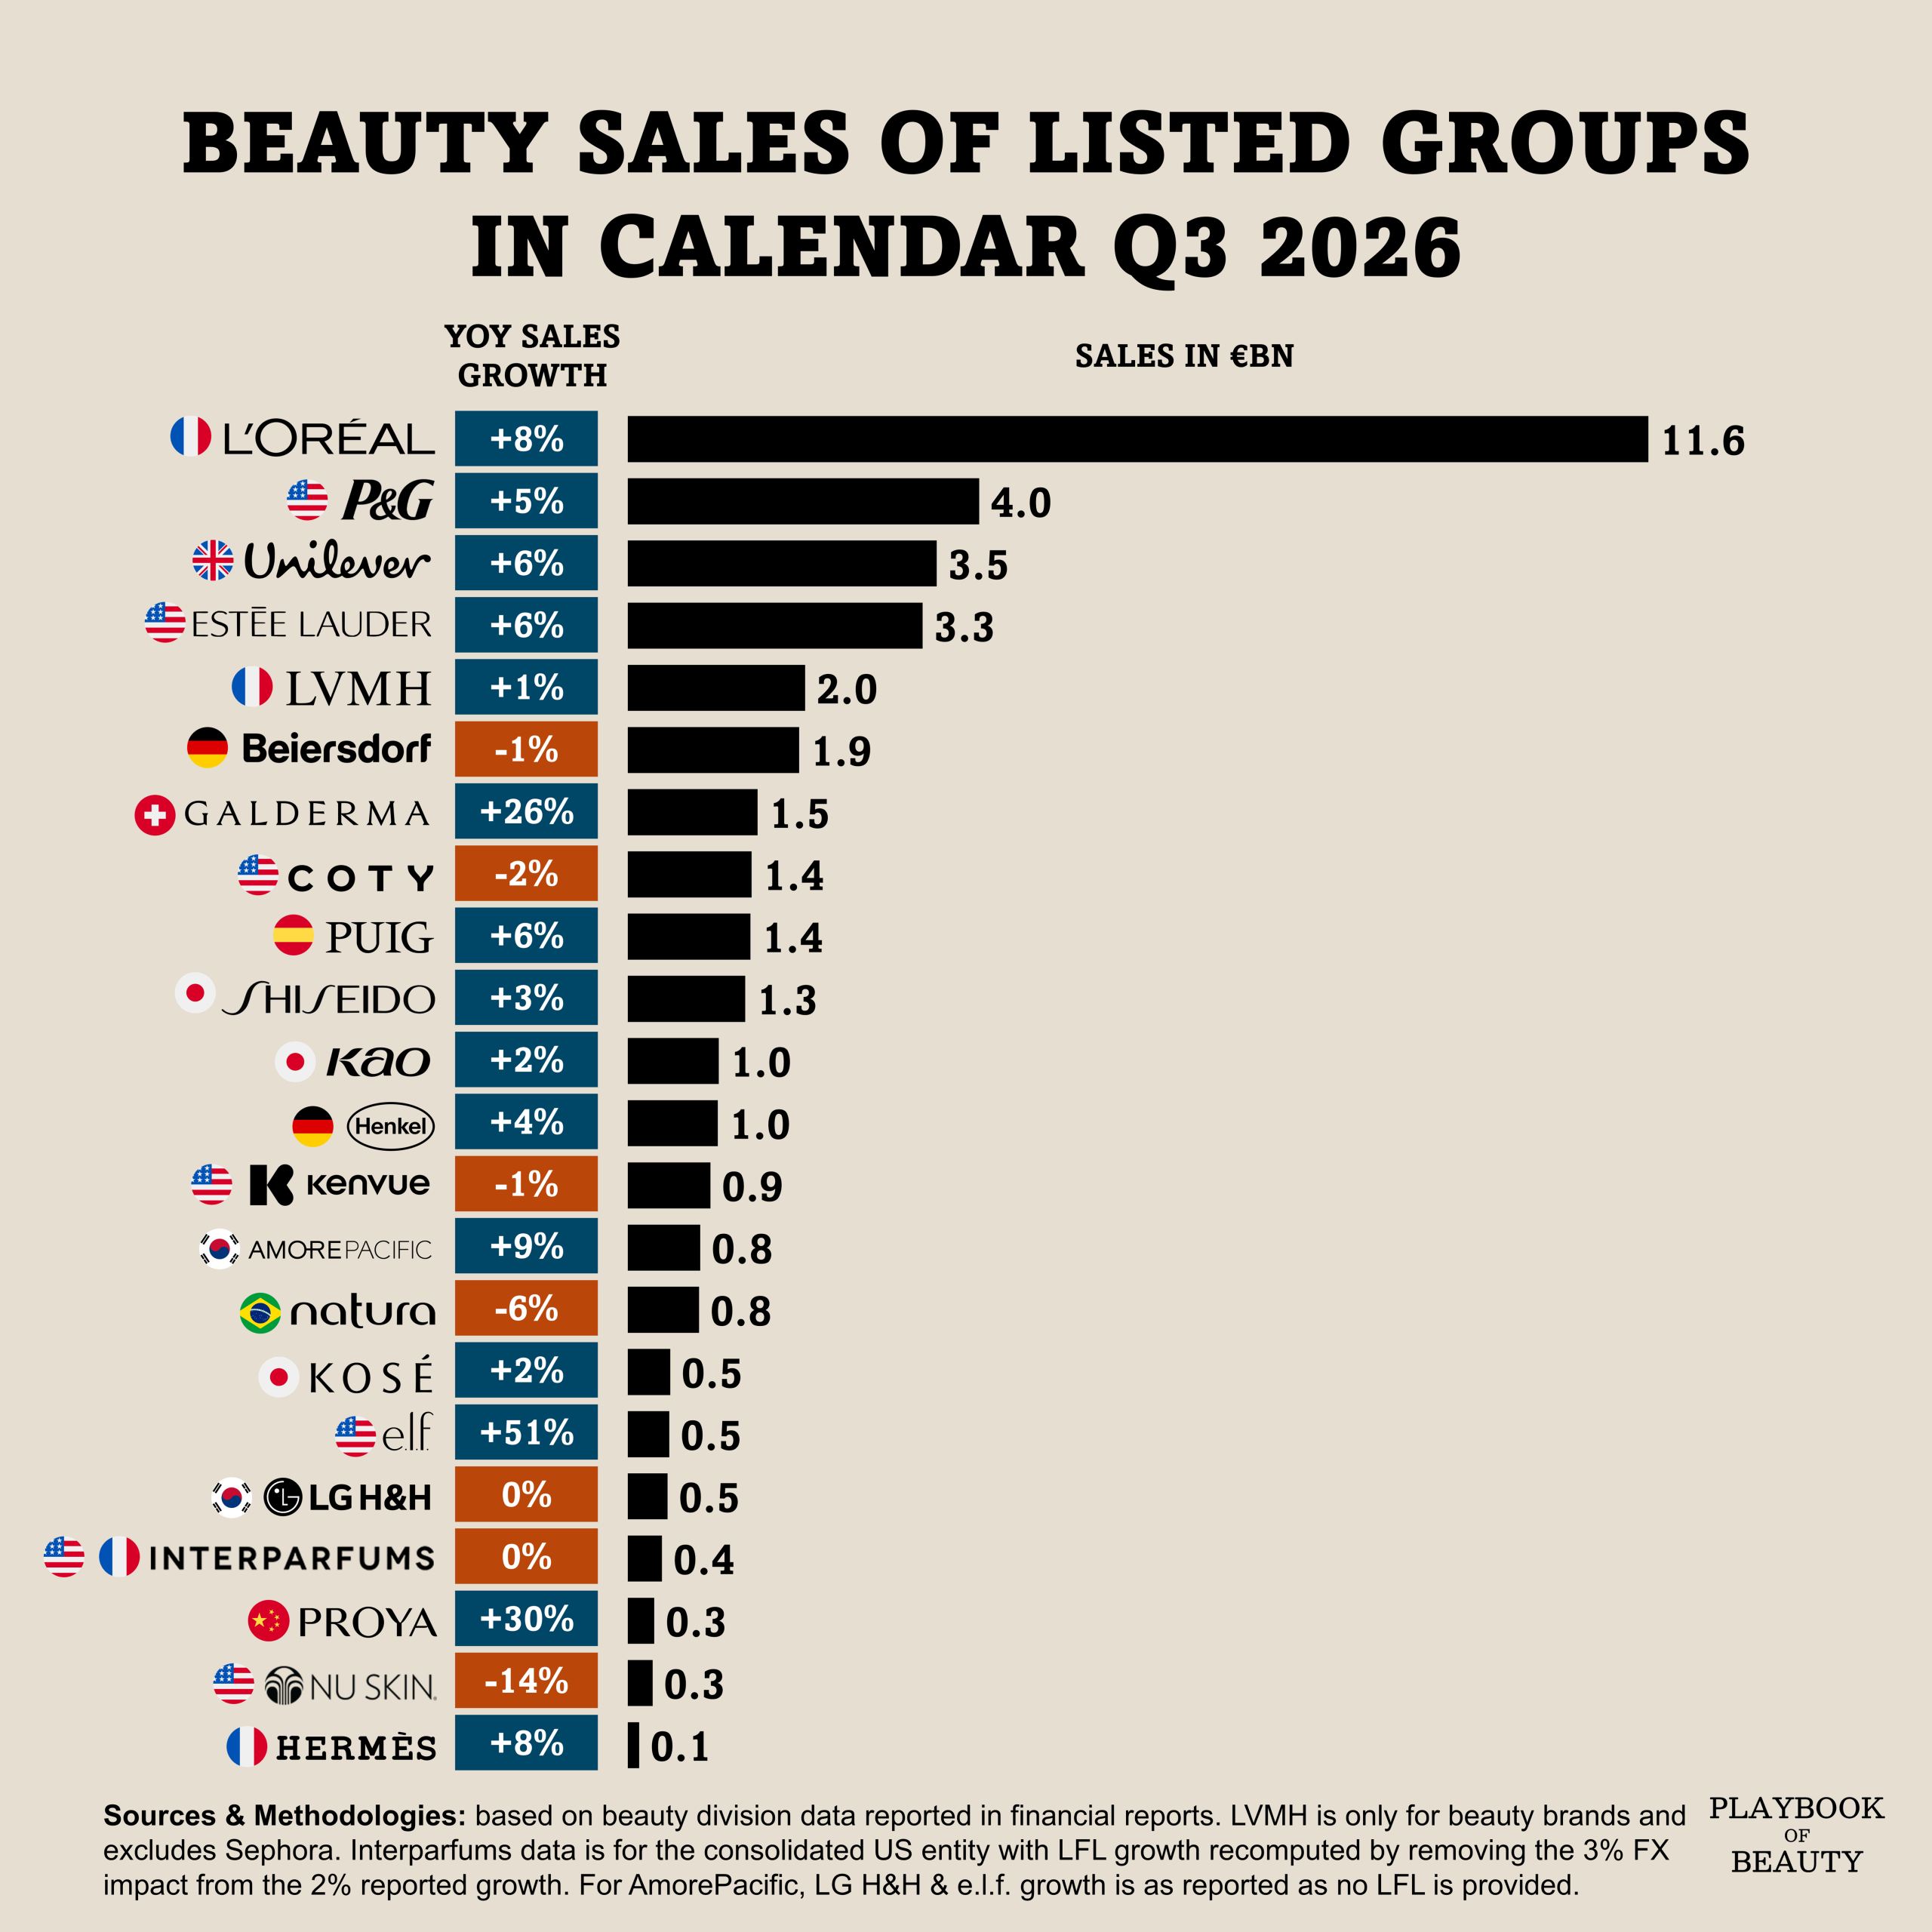
Derma, haircare and fragrance continued to drive growth. L’Oréal and Beiersdorf both reported double-digit growth in derma, while Unilever’s haircare accelerated to double digits and Estée Lauder’s fragrance sales rose 20% organically. China and APAC improved for several groups.
L’Oréal reached €11.56bn in Q3 sales, up 7.7% LFL adjusted. Professional Products & Dermatological Beauty each grew 13.9%, Luxe 7.0% and Consumer Products 3.8%. Fragrance remained a major luxury driver and premium haircare supported Professional Products. SAPMENA-SSA led at +19.5%, followed by Europe at +8.9%, North Asia at +7.8% and North America at +5.6% while LATAM fell 3.0%, affected by supply disruptions and stock adjustments in Mexico.
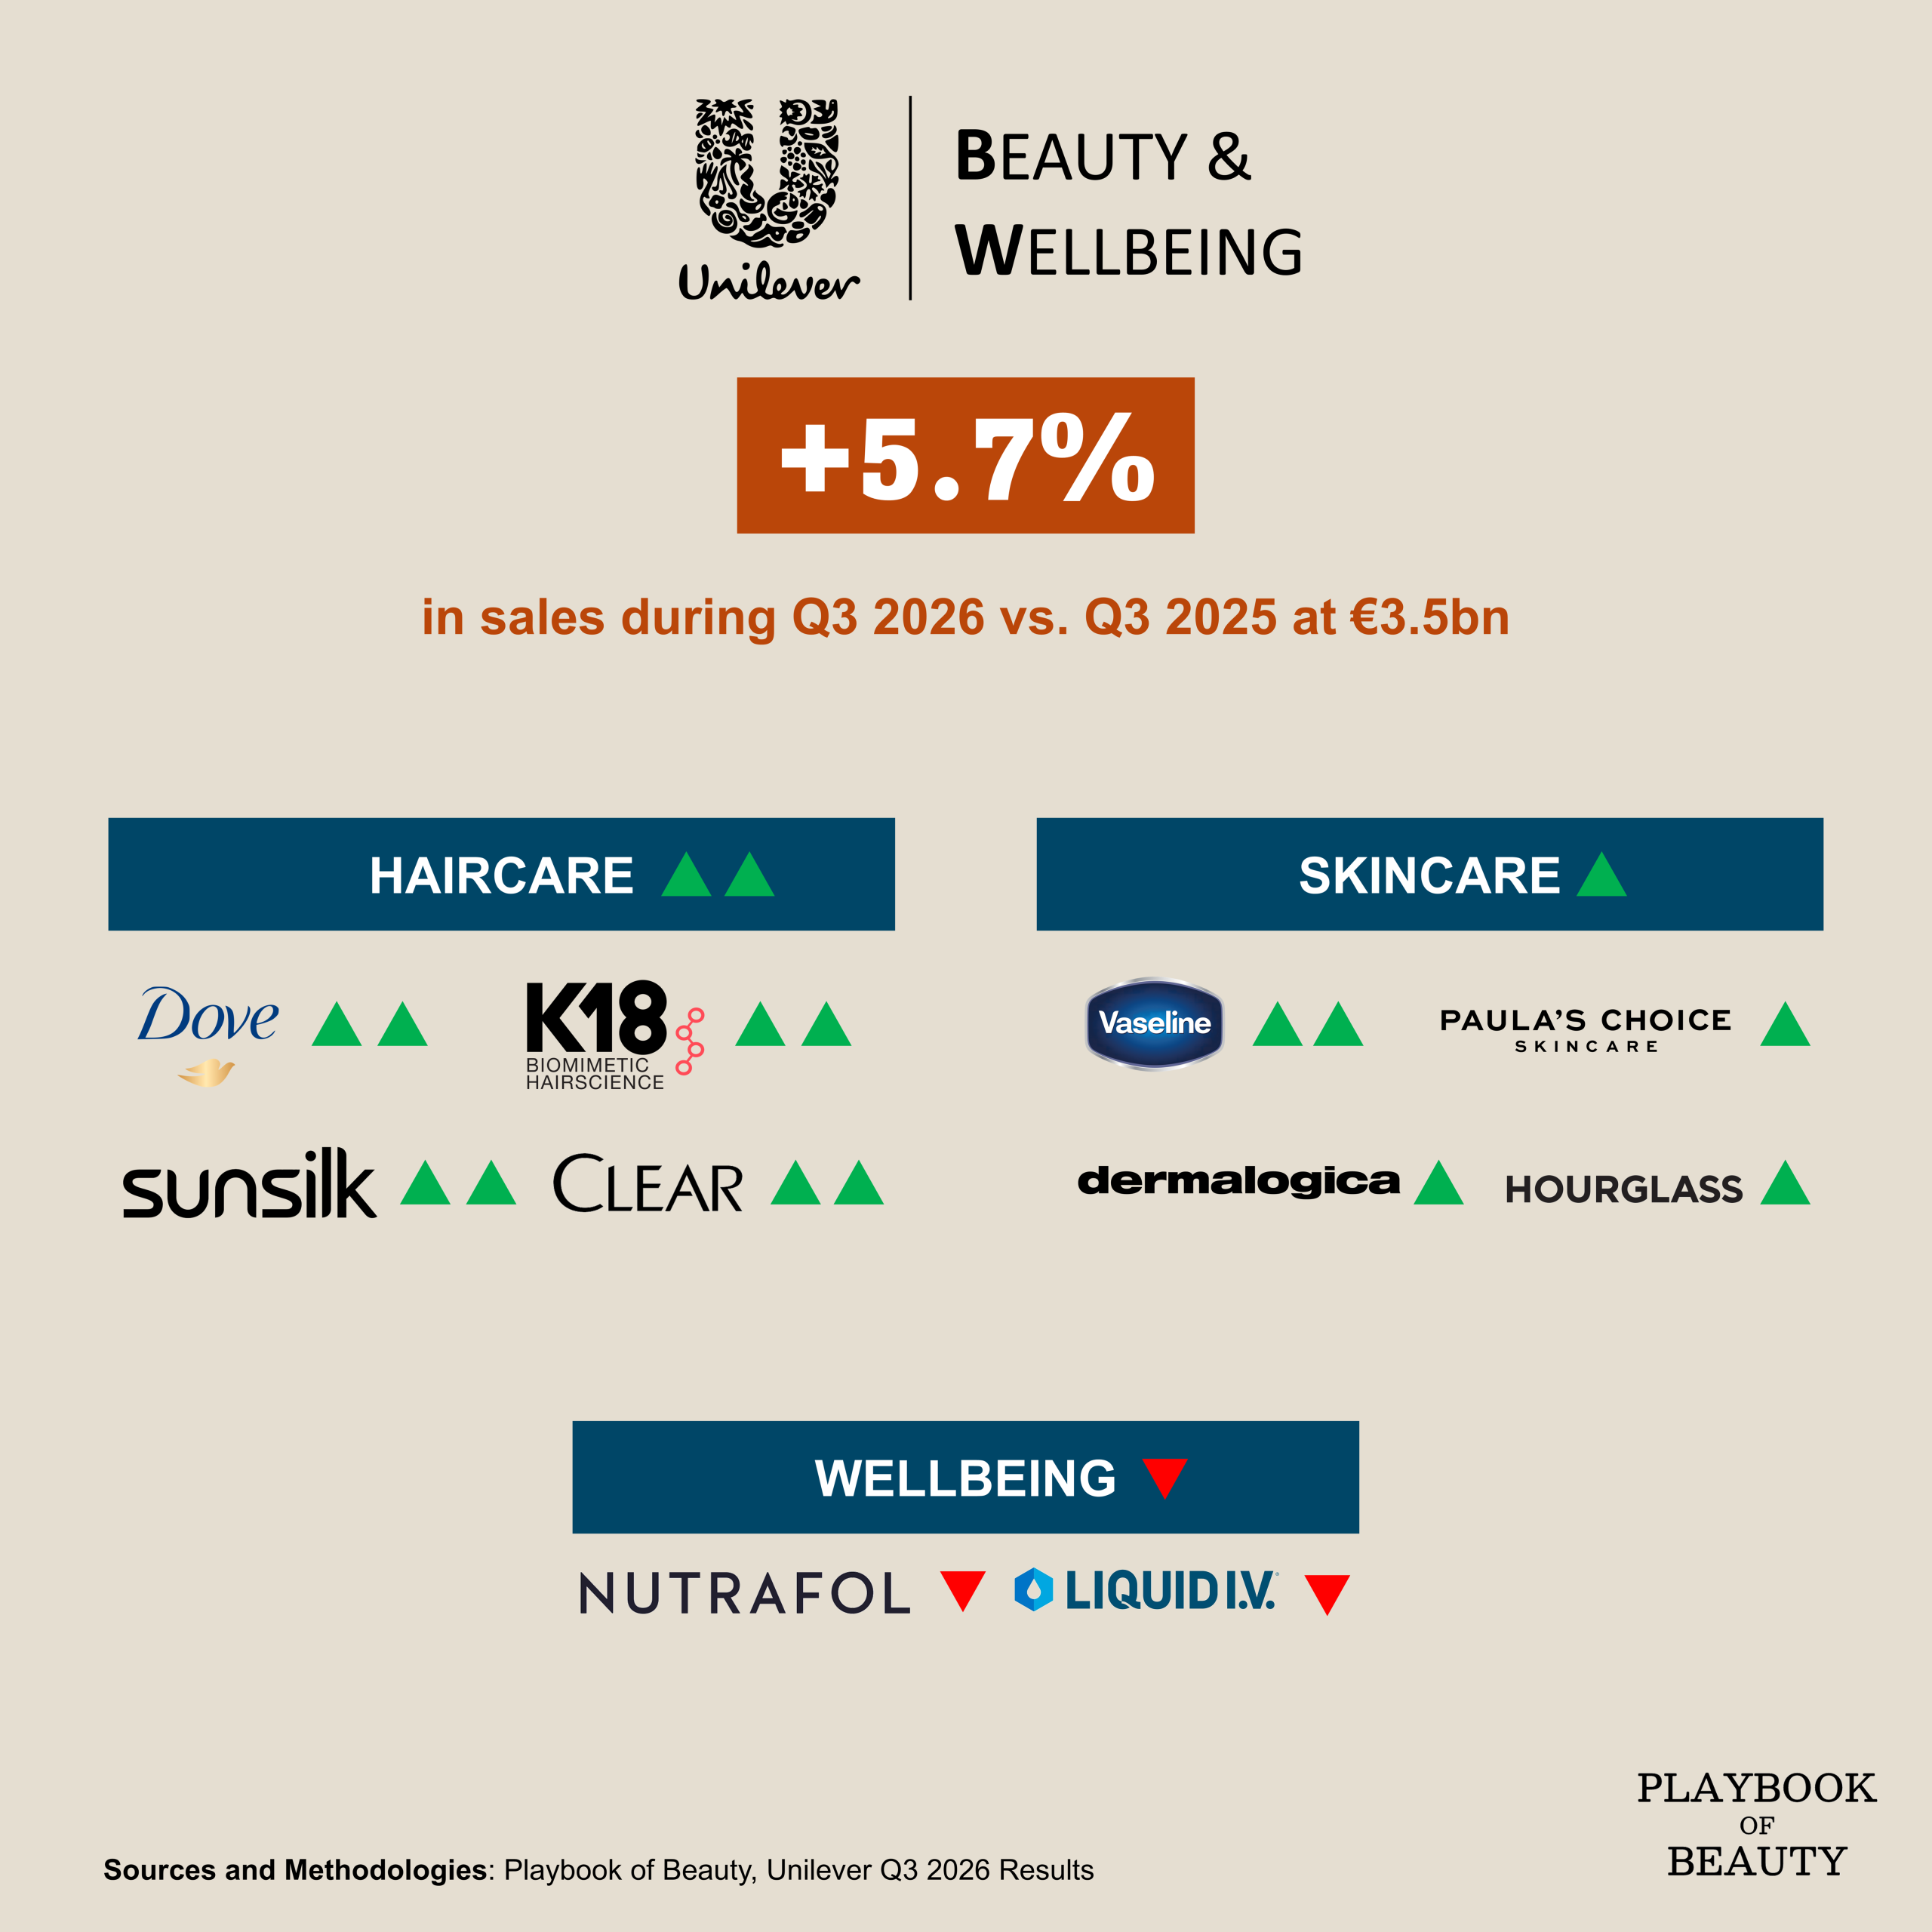
Unilever Beauty grew 5.7% to €3.5bn, with double-digit haircare growth and mid-single-digit skincare growth.
Estée Lauder’s recovery broadened: organic sales grew 6% to €3.34bn ($3.72bn). Fragrance rose 20%, skincare 4% and makeup 1%. APAC grew 10% and mainland China 9%, helped by innovation, shopping events, broader consumer reach and travel retail. The company raised its FY27 organic growth outlook to 4 to 5.5%.
LVMH P&C returned to growth at +1% organically, reaching €2.01bn.
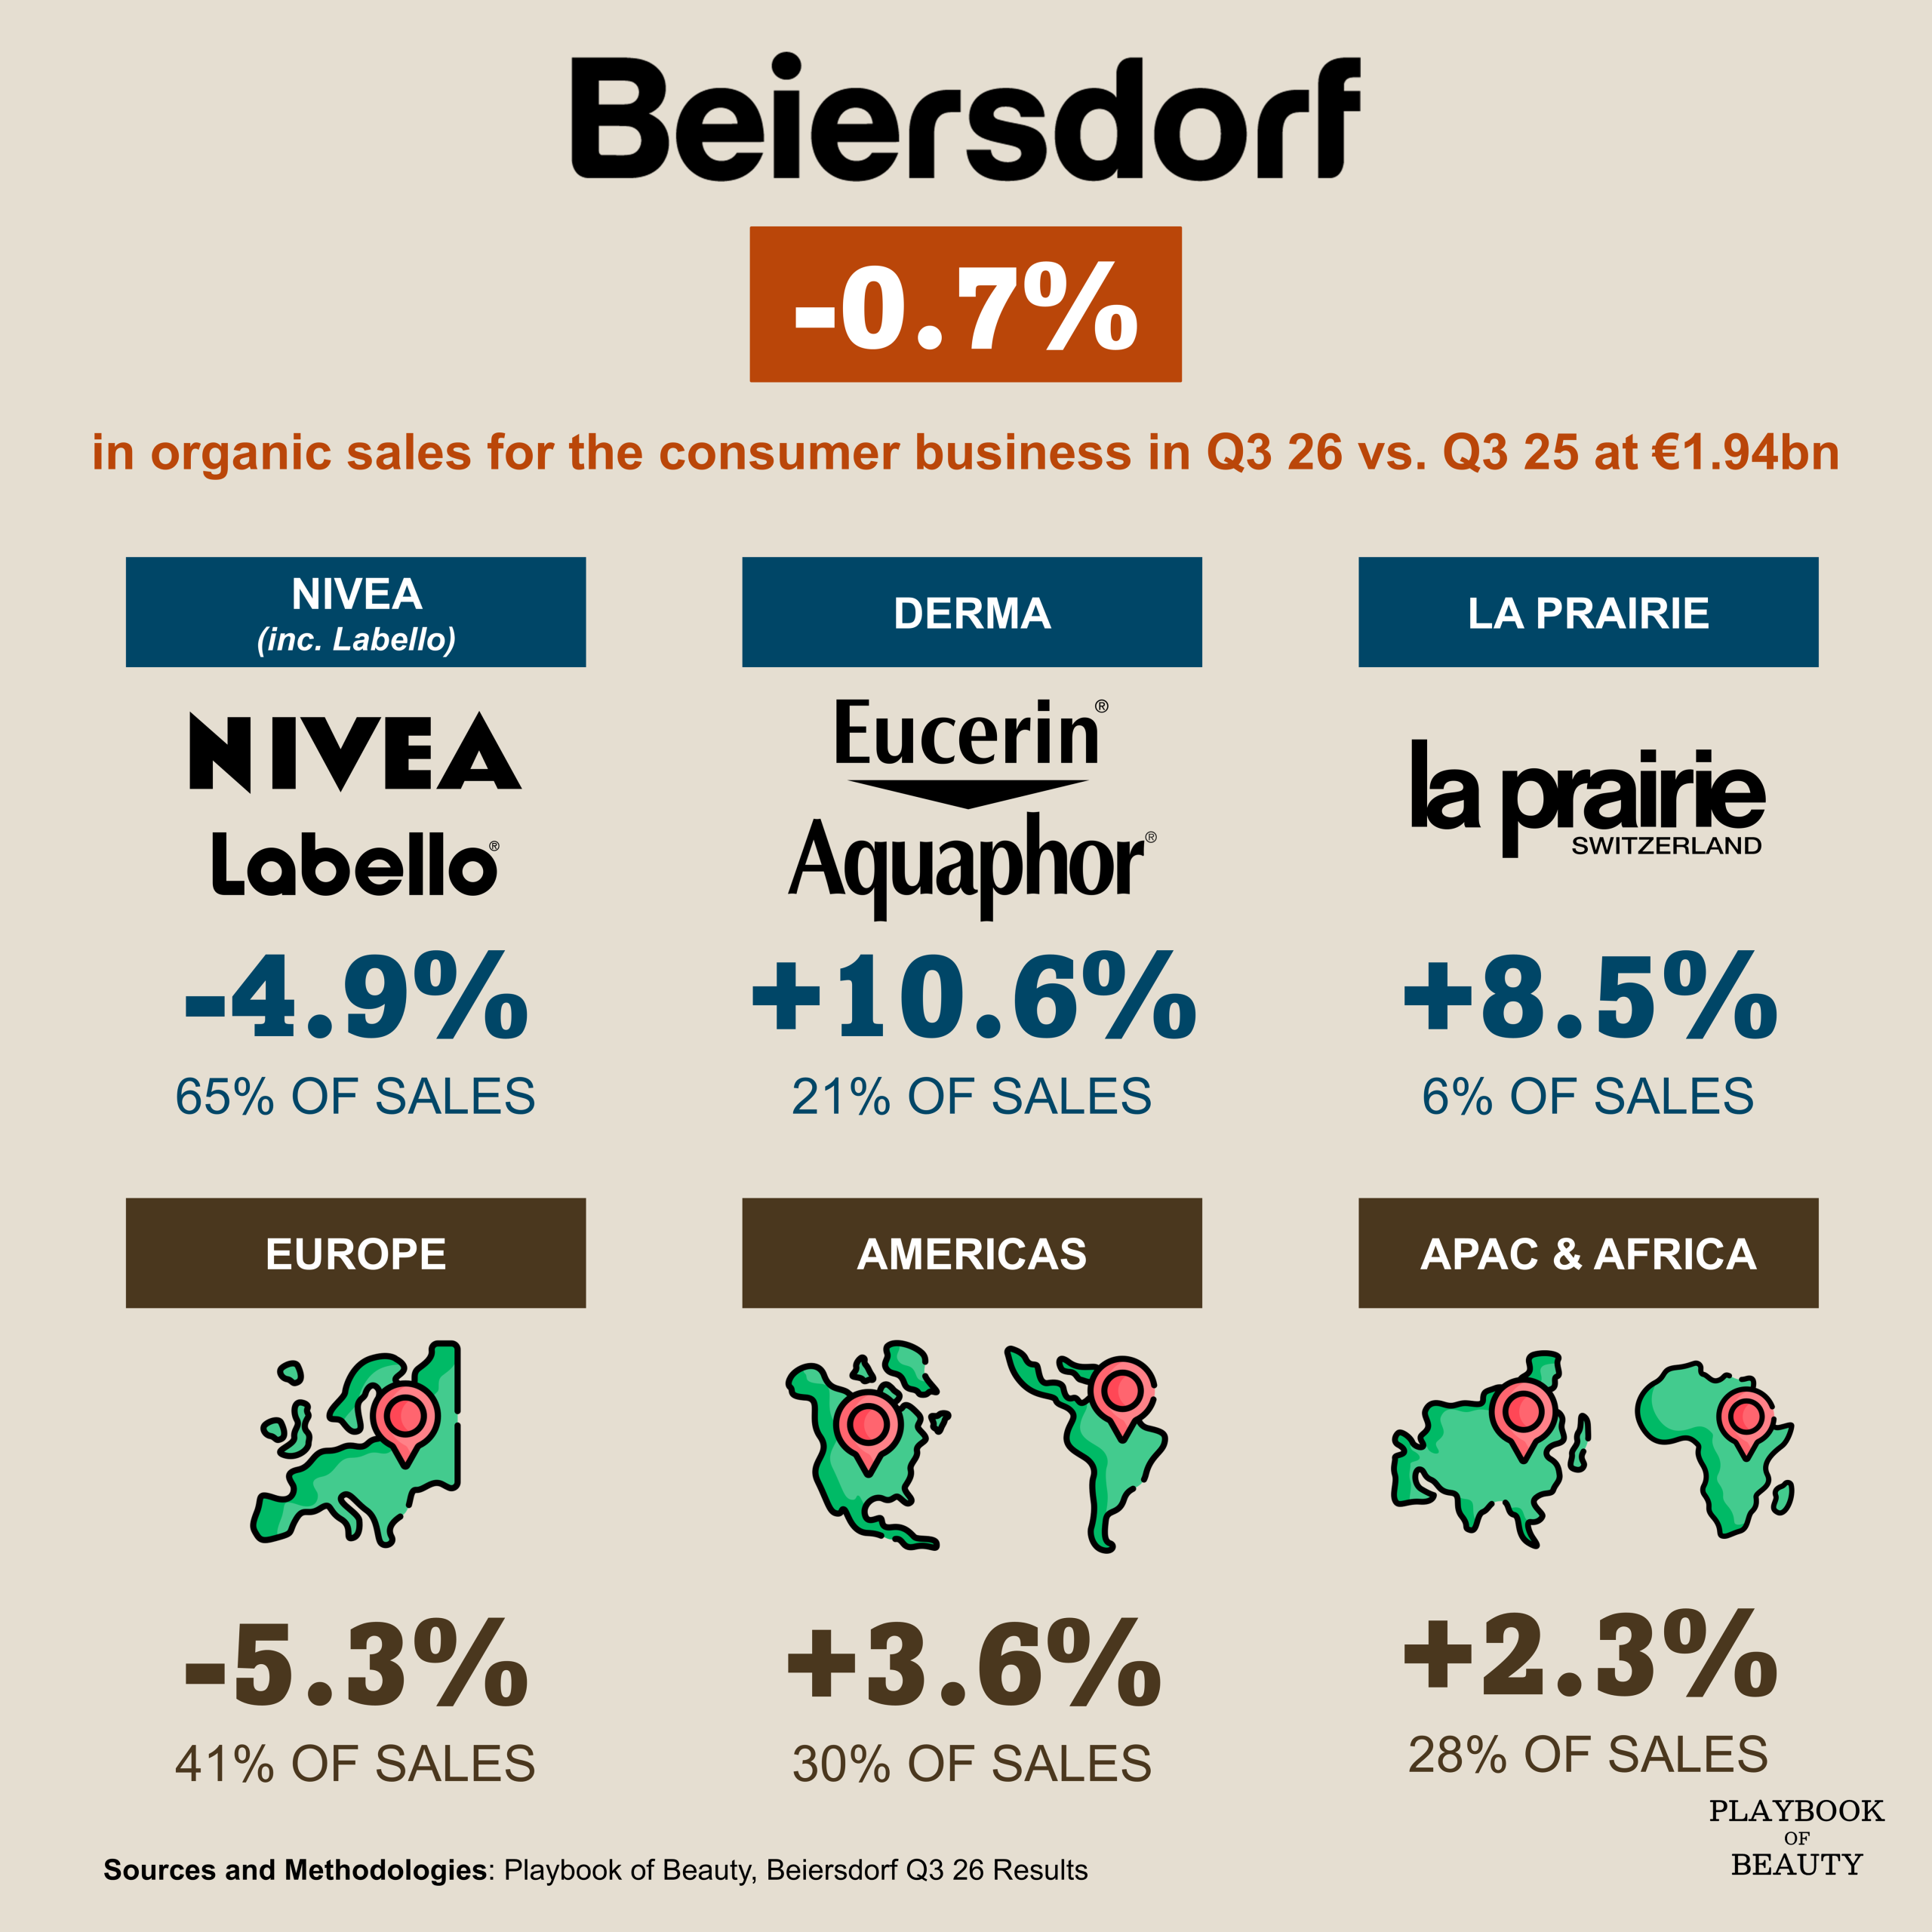
Beiersdorf Consumer declined 0.7% organically to €1.94bn. Derma grew 10.6%, but NIVEA and Labello fell 4.9%, affected by retailer disputes and destocking.
Galderma grew 26.0% at constant currency to €1.47bn ($1.6bn), led by Therapeutic Dermatology at +58.9%. Injectable Aesthetics and Dermatological Skincare both grew 15%+.
Coty remains in transition, with sales down 2% LFL to €1.40bn ($1.56bn). Prestige fell 1% and Consumer Beauty 3%, although the six core Prestige brands grew 5%. APAC rose 8%, supported by China, SSA and travel retail, while EMEA fell 5% and Americas were flat.
Puig grew 5.6% LFL to €1.39bn. Makeup led at +16.1%, while Fragrance and Fashion rose 3.9%, supported by niche fragrances and Carolina Herrera. Skincare fell 0.8% as double-digit derma growth could not offset soft premium skincare. APAC grew 12.9%, the Americas 6.2% and EMEA 3.8%.
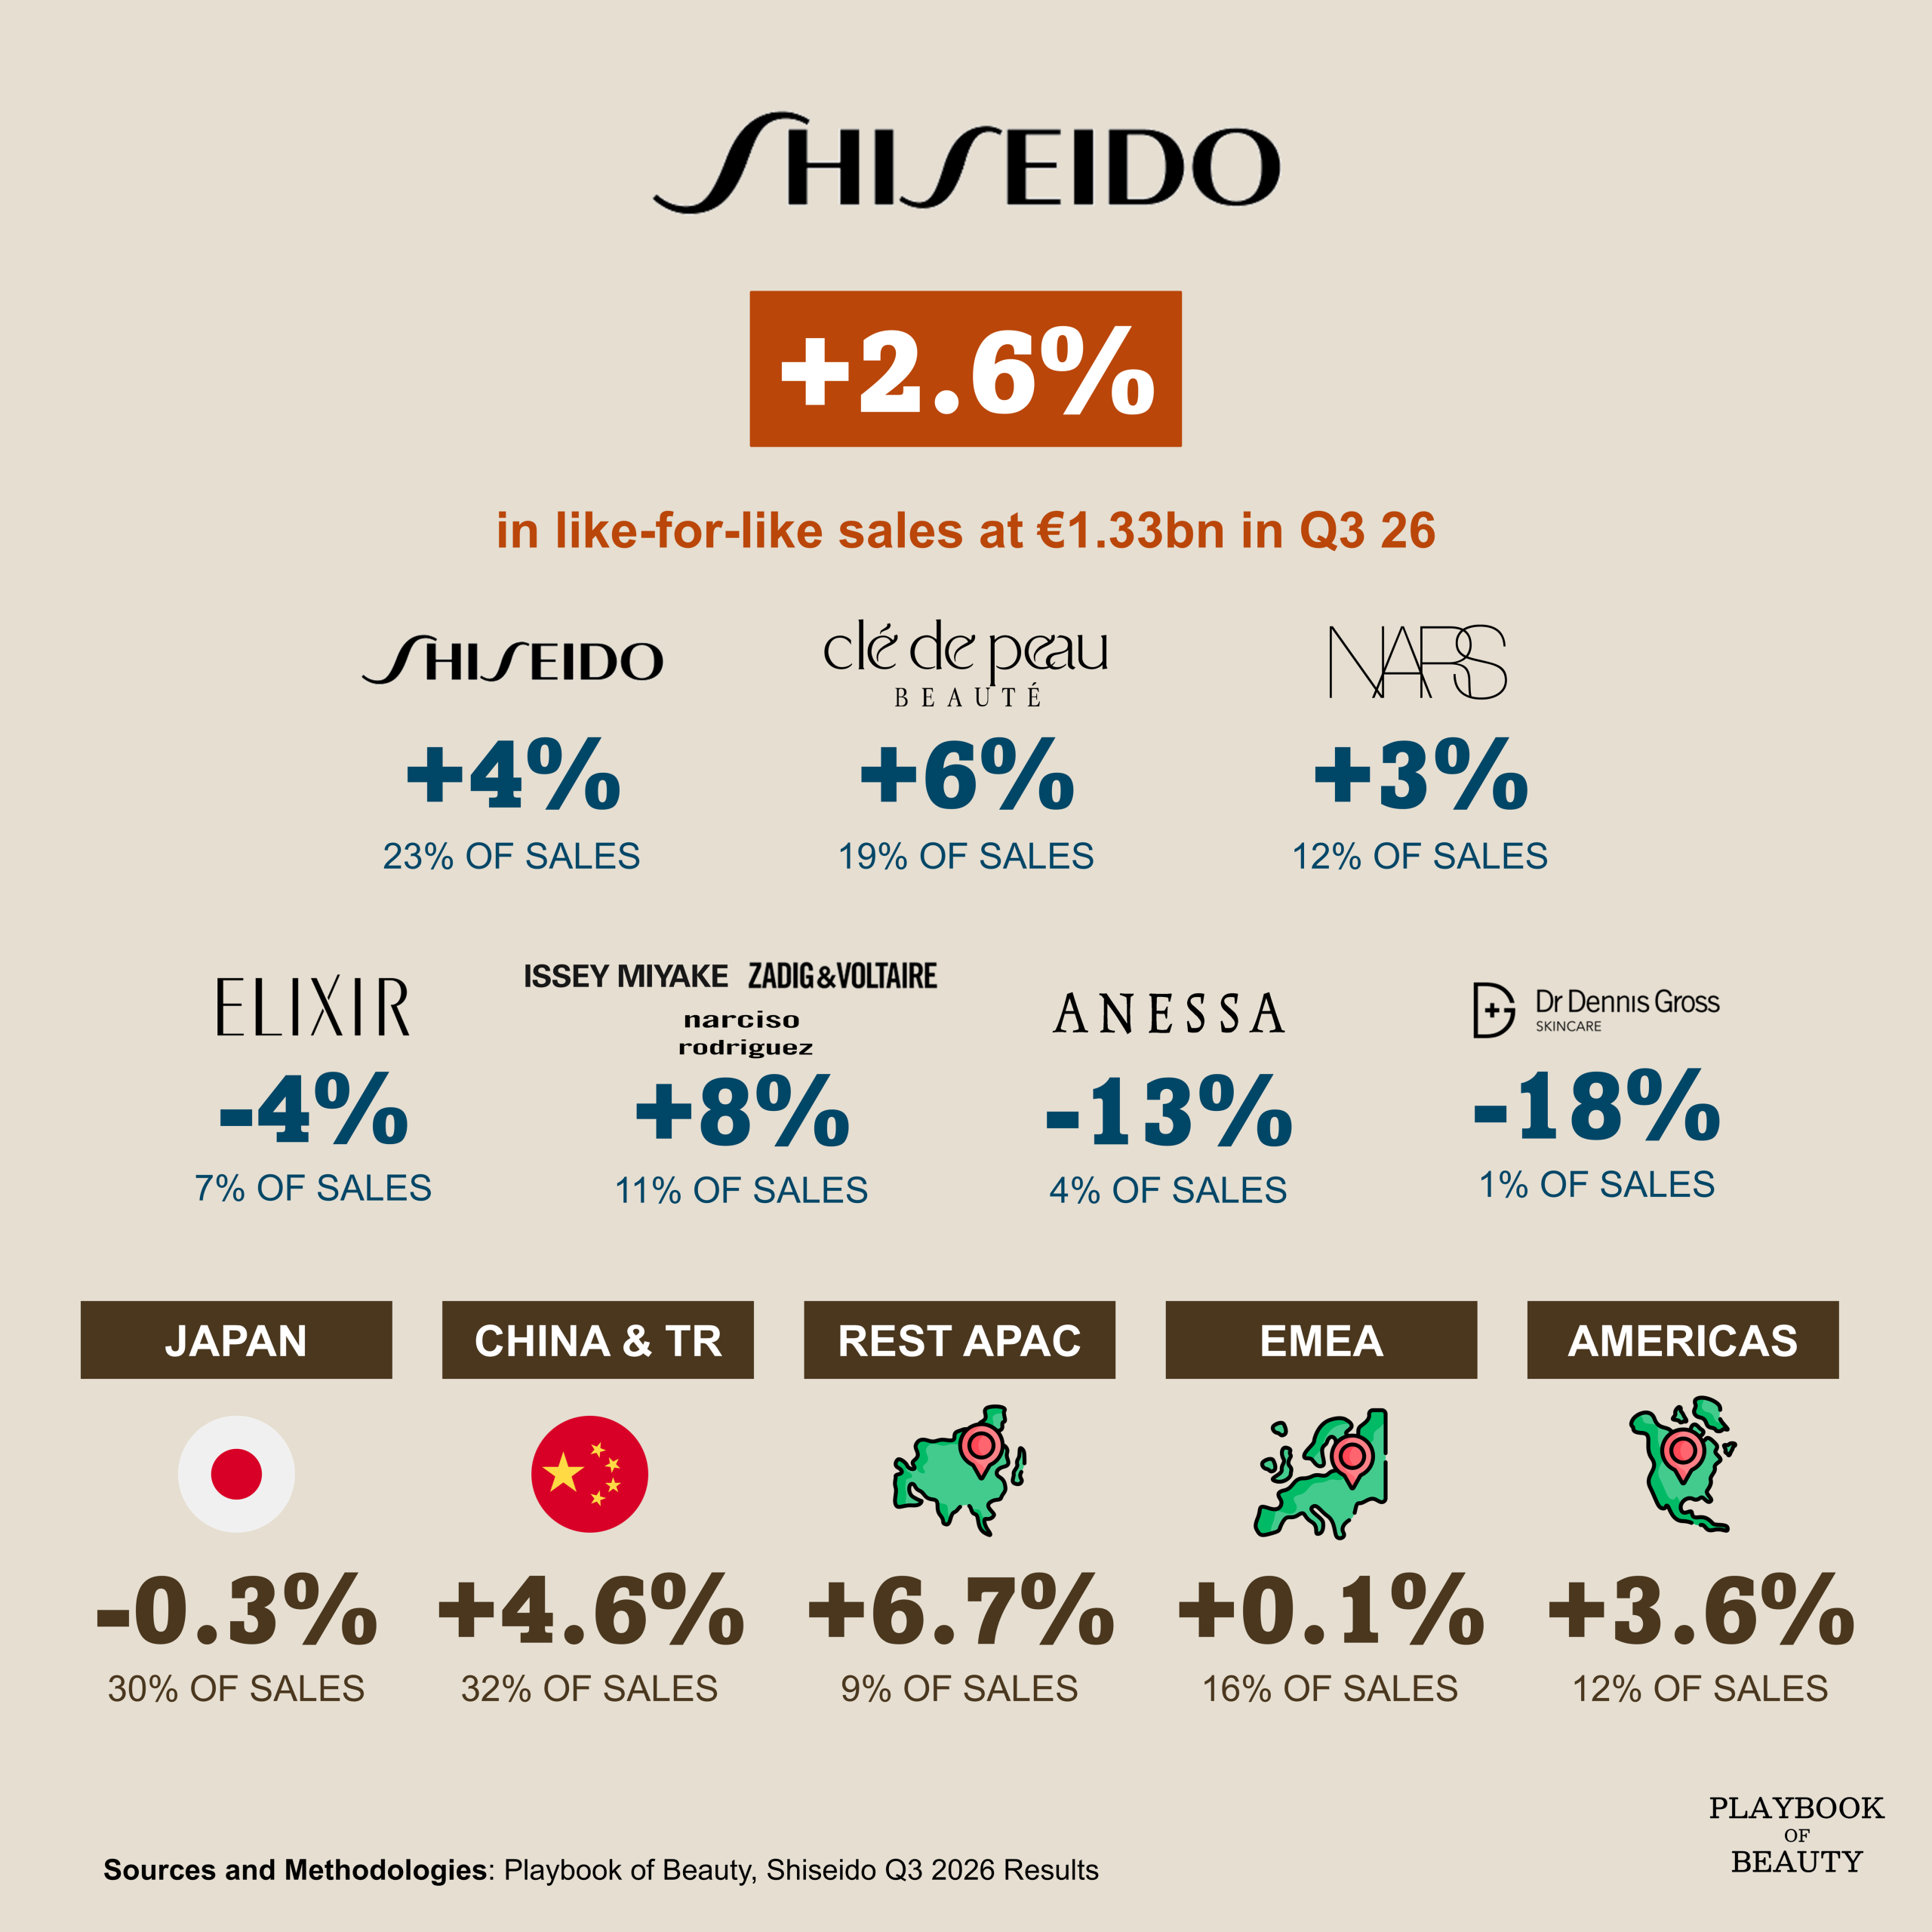
Shiseido’s sales rose 2.6% LFL to €1.33bn (¥242.2bn), while core operating profit more than tripled and margin rose to 9.5% from 3.0%. China & TR grew 4.6% despite lower Chinese consumer purchases. APAC grew 6.7% and the Americas 3.6%. Japan was nearly flat. Shiseido lowered its FY LFL growth forecast from 3% to 1%.
Subscribe to my newsletter for weekly insights on the beauty industry. Link in the comments.